Bad Credit Home Loans in Kentucky: 5 Mortgage Options for 2026 (Scores From 500)

Bad credit mortgage options in Kentucky - FHA, VA, USDA, KHC and Non-QM loans

By Joel Lobb, Mortgage Loan Officer | NMLS #57916 | Louisville, KY — Updated October 2026

Yes, you can get a mortgage with bad credit in Kentucky. I have been closing loans for Kentucky borrowers since 2001, including many with scores in the 500s and low 600s, and the single biggest mistake I see is buyers disqualifying themselves before they ever apply. Several government-backed programs were built specifically for borrowers with credit challenges, and one of them accepts scores as low as 500.

Below are the five bad credit mortgage options Kentucky homebuyers are actually using in 2026, with the real credit score minimums, down payment requirements, and bankruptcy/foreclosure waiting periods for each — verified against current agency guidelines, not recycled from old blog posts.

Low score? Get a straight answer today: a free soft-pull review with no hit to your credit.

📞 Call 502-905-3708💬 Text Joel✉️ Email

Kentucky Bad Credit Mortgage Options at a Glance

Program Minimum Credit Score Down Payment Best For
FHA500 (10% down) / 580 (3.5% down)3.5%–10%Lowest scores, past credit issues
VANo VA minimum (lender overlays vary)$0Veterans, active duty, surviving spouses
USDANo published USDA minimum (lender overlays vary)$0Buyers in eligible rural Kentucky areas
KHC + $12,500 DAP620 (FHA/VA/USDA first mortgage)Covered up to $12,500Buyers short on cash to close
Non-QMVaries (often 580–620+)10%–20%Self-employed, recent bankruptcy or foreclosure

1. FHA Loans — Credit Scores From 500

FHA is the workhorse for Kentucky buyers with damaged credit, because HUD’s own rules go lower than any other mainstream program:

  • Score 580 or above: 3.5% minimum down payment
  • Score 500–579: 10% minimum down payment

FHA also allows higher debt-to-income ratios than conventional financing, accepts non-traditional credit for borrowers with thin files, and does not price the loan the way conventional lenders do — a 590 score does not carry the punishing rate adjustments it would on a conventional loan.

What FHA looks at beyond the score: a two-year work history, 12 months of clean recent payment history (especially rent), and how you have handled credit since any past problems. Collections do not automatically disqualify you. Mortgage insurance (upfront and monthly MIP) applies. The 2026 FHA loan limit is $541,287 for every Kentucky county.

Waiting periods: 2 years from a Chapter 7 discharge (as little as 12 months with documented extenuating circumstances), 12 months of on-time payments into a Chapter 13 plan with court permission, and 3 years after a foreclosure.

2. VA Loans — No Minimum Score From the VA

If you are a veteran, active-duty service member, or eligible surviving spouse, the VA loan is almost always your strongest option with imperfect credit. The VA itself sets no minimum credit score — the 620 figure you see quoted online is a lender overlay, and overlays vary widely from lender to lender. As a broker, I can shop your file to lenders with the most flexible VA credit standards rather than being stuck with one company’s overlay.

  • Down payment: $0
  • Mortgage insurance: none (a one-time VA funding fee applies, which is waived for many disabled veterans)
  • Waiting periods: 2 years after Chapter 7 bankruptcy or foreclosure; 12 months into a Chapter 13 plan
  • Requirements: Certificate of Eligibility, residual income test, stable income; a wood-destroying insect inspection is standard on Kentucky VA purchases

As an Army veteran myself, I have closed hundreds of VA loans across Kentucky. If you served, you earned this benefit — do not let one lender’s overlay talk you out of using it.

3. USDA Loans — Zero Down in Eligible Rural Areas

Here is something most bad-credit articles get wrong: USDA does not publish a minimum credit score. The “620–640 required” claim repeated all over the internet comes from lender overlays and outdated guidance, not USDA’s actual handbook. USDA evaluates your credit history by topic — payment patterns, collections, past housing history — and files can be approved through GUS or manually underwritten with documented compensating factors. For score targets and how GUS treats them, see the credit score you need for a Kentucky USDA loan.

  • Down payment: $0 — 100% financing
  • Location: the property must be in a USDA-eligible area, which covers most of Kentucky outside the Louisville, Lexington, and Northern Kentucky urban cores — check a property address here
  • Income limits (effective July 13, 2026): $122,800 for households of 1–4 and $162,100 for households of 5–8 in most Kentucky counties; $128,600 / $169,800 in Boone, Bracken, Campbell, Gallatin, Kenton, and Pendleton counties — see the full county list
  • Fees: 1.00% upfront guarantee fee (financeable) and a 0.35% annual fee paid monthly
  • Waiting periods: generally 3 years after Chapter 7 bankruptcy or foreclosure (less with documented extenuating circumstances); 12 months of on-time payments into a Chapter 13 plan
  • Collections: non-medical collections over $2,000 in aggregate require a payment plan or an imputed payment in your ratios; medical collections and charge-offs are excluded from that test

4. KHC Loans With $12,500 Down Payment Assistance

Kentucky Housing Corporation pairs an FHA, VA, USDA, or conventional first mortgage with its Down Payment Assistance Program (DAP) — and the 2026 numbers are better than what most older articles report:

Assistance amountUp to $12,500, in $100 increments (increased from the old $10,000)
StructureRepayable second mortgage — 15-year term at KHC’s published fixed rate (roughly $95–$100/month at recent program rates). It is not a grant and not forgivable.
Credit score620 minimum with an FHA, VA, or USDA first mortgage; 660 for conventional
Use of fundsDown payment, closing costs, and prepaids
LimitsIncome and purchase price limits apply by county; KHC updates these periodically, so we verify the current limits when you apply

For a buyer with a 620 score and very little saved, an FHA first mortgage plus KHC’s $12,500 can cover the entire 3.5% down payment on a typical Kentucky purchase with money left toward closing costs. This combination is how a large share of my credit-challenged clients actually get to the closing table.

5. Non-QM Loans — When You Do Not Fit the Government Box

Non-Qualified Mortgage (Non-QM) programs exist for borrowers the standard programs cannot serve: self-employed buyers who write off most of their income, 1099 contractors and gig workers, investors, and anyone with a very recent credit event.

  • Income documentation: 12–24 months of bank statements, rental income (DSCR), or asset depletion instead of tax returns
  • Waiting periods: as little as 1 year after a bankruptcy or foreclosure — some programs go shorter
  • Down payment: typically 10%–20%
  • Trade-off: higher rates and fees than government-backed loans, since these are not insured programs

I treat Non-QM as a bridge, not a destination: get into the house now, rebuild the credit profile, then refinance into FHA or conventional when you qualify.

Zero Down With Bad Credit: First-Time Buyer Options

The most common question I get from first-time buyers is whether bad credit and no savings rules them out. It does not. Three paths get Kentucky buyers into a home with little or nothing down:

  • USDA (rural areas): $0 down, no USDA minimum score. Best fit if the home is outside the Louisville, Lexington, and Northern Kentucky cores and your household is under the income limit.
  • VA (veterans and service members): $0 down, no VA minimum score, no monthly mortgage insurance.
  • FHA + KHC down payment assistance (620+ score): 3.5% down on the FHA loan, with KHC’s up-to-$12,500 second mortgage covering the down payment and part of the closing costs.

Below 620 and not a veteran? A USDA loan in an eligible county is usually the strongest zero-down option. Otherwise, FHA with a family gift and seller-paid closing costs can get you in with very little of your own money. See my full Kentucky first-time home buyer guide for the rest of the steps.

What Kentucky Lenders Actually Look At Beyond the Score

Two borrowers with identical 590 scores can get opposite decisions. Underwriters weigh:

  • The last 12 months. Recent clean payment history — especially rent and any active accounts — matters more than a three-year-old charge-off.
  • The story behind the score. A medical event or divorce with recovery since reads very differently than ongoing late payments.
  • Collections and judgments. Most do not have to be paid off to close, but each program has its own rules for how they count.
  • Debt-to-income ratio and residual income. Lower ratios and cash reserves are the compensating factors that get marginal files approved.

If your middle score is close to a program cutoff, do not guess. I run a soft-pull review and can often map out the two or three specific moves (paying a card below 25% of its limit, disputing an error, adding a rent history) that raise a score enough to qualify — sometimes within 30 to 60 days. If bankruptcy is part of your history, see my full guide to getting a Kentucky USDA loan after bankruptcy or foreclosure. Not sure where your score stands? Here is how to get a free credit score for a mortgage.

Frequently Asked Questions

What is the lowest credit score for a home loan in Kentucky?

500, using an FHA loan with 10% down. With a 580 score, the FHA down payment drops to 3.5%. VA and USDA set no agency minimum at all, though individual lenders apply their own overlays.

Can I get down payment assistance with bad credit?

KHC’s $12,500 Down Payment Assistance requires a 620 minimum score with an FHA, VA, or USDA first mortgage. Below 620, the assistance is off the table for now, but an FHA loan with a family gift or seller-paid closing costs can fill the same gap.

How soon after bankruptcy can I buy a house in Kentucky?

FHA and VA: 2 years after a Chapter 7 discharge, or 12 months of on-time Chapter 13 plan payments. USDA: generally 3 years after Chapter 7. Non-QM: as little as 1 year. Extenuating-circumstance exceptions can shorten several of these.

Does USDA have a minimum credit score?

No. USDA does not publish a minimum credit score. The 620–640 figures quoted online are lender overlays, which vary by lender. USDA looks at your overall credit history and allows manual underwriting with compensating factors.

Can a first-time buyer get a zero-down loan with bad credit?

Yes. USDA (in eligible rural areas) and VA (for veterans) both offer $0 down and set no agency minimum score. With a 620 or higher score, FHA plus KHC’s up to $12,500 down payment assistance can cover the down payment as well.

Does bad credit mean a much higher interest rate?

On government-backed loans (FHA, VA, USDA), far less than most people fear — these programs do not apply the steep score-based pricing that conventional loans do. Non-QM loans do carry meaningfully higher rates.

Do I have to pay off my collections first?

Usually not. FHA, VA, and USDA each have their own treatment of collections, and medical collections are broadly excluded. Bring me the credit report and I will tell you exactly which accounts, if any, need attention before closing.

Get a Same-Day Answer on Your Credit Situation

Do not guess which program fits your credit profile — and do not let a single lender’s “no” stand as the final answer. As a broker, I can place your file with the lender whose overlays match your situation. Pre-approvals are free and usually same-day.

📞 Call or Text: 502-905-3708
📧 Email: kentuckyloan@gmail.com
🌐 Website: www.mylouisvillekentuckymortgage.com

Joel Lobb — Mortgage Loan Officer
EVO Mortgage
10602 Timberwood Cir, Ste 3, Louisville, KY 40223
NMLS #57916 | Company NMLS #1738461
NMLS Consumer Access | Equal Housing Lender

This is not a commitment to lend. All loans are subject to credit approval and program requirements. This website is not endorsed by FHA, VA, USDA, HUD, or any government agency.

 Buying Your First House in Kentucky: Loan Programs and Requirements

Buying Your First House in Kentucky with the recommend mortgage loan programs below

A Guide to Buying Your First House in Kentucky: Loan Programs and Requirements
Buying your first home in Kentucky is an exciting milestone, but it can also feel overwhelming. Fortunately, there are several loan programs and resources available to make the process smoother. This guide will walk you through the most popular loan programs and their requirements, helping you take confident steps toward homeownership.

  1. FHA Loan: A Flexible Option for First-Time Buyers
    The Federal Housing Administration (FHA) loan is popular among first-time homebuyers due to its lenient requirements.
    Key Requirements:
    Credit Score: Minimum of 580 with 3.5% down payment. Scores between 500-579 require a 10% down payment.
    Down Payment: 3.5% minimum.
    Mortgage Insurance: Requires both an upfront premium and monthly mortgage insurance.
    Debt-to-Income (DTI) Ratio: Typically up to 43%.
    Benefits:
    Lower credit score requirements.
    Smaller down payment.
    Flexible income guidelines.
  2. VA Loan: No Money Down for Eligible Veterans
    The VA Loan is a fantastic option for Kentucky veterans, active-duty service members, and their spouses. It’s backed by the Department of Veterans Affairs.
    Key Requirements:
    Credit Score: No official minimum, but lenders often look for 580-620.
    Down Payment: $0 (no down payment required).
    Certificate of Eligibility (COE): Required to prove eligibility.
    Mortgage Insurance: None, but a VA funding fee applies.
    Benefits:
    No down payment.
    No private mortgage insurance (PMI).
    Competitive interest rates.
  3. USDA Loan: Ideal for Rural Homebuyers
    The USDA Rural Development Loan is perfect for buyers looking to live in rural or suburban areas in Kentucky.
    Key Requirements:
    Credit Score: Generally 620 or higher.
    Income Limits: Household income must not exceed the area’s median income.
    Location: The property must be in a USDA-eligible rural area.
    Debt-to-Income Ratio: Up to 41%.
    Benefits:
    $0 down payment.
    Affordable mortgage insurance.
    Competitive fixed interest rates.
  4. Kentucky Housing Corporation (KHC) Programs
    The Kentucky Housing Corporation offers down payment assistance and loan options to first-time buyers.
    KHC Loan Options:
    KHC FHA or Conventional Loans: Competitive rates and assistance programs.
    Down Payment Assistance: Up to $10,000 in assistance for qualifying borrowers.
    Key Requirements:
    Credit Score: Minimum 620 for most programs.
    Income Limits: Vary by program and household size.
    Property Type: Must be a primary residence.
  5. Conventional Loan: A Strong Option for Higher Credit Scores
    Conventional loans, offered through private lenders, are great for buyers with stronger credit profiles.
    Key Requirements:
    Credit Score: Minimum 660.
    Down Payment: As low as 3% with first-time buyer programs.
    Mortgage Insurance: Required if down payment is less than 20%.
    Benefits:
    Lower interest rates for strong credit scores.
    Option to cancel PMI once equity reaches 20%.
    Check Your Credit Score: Understand where you stand. If needed, work on improving your score before applying.
    Determine Your Budget: Get pre-approved for a mortgage to understand your price range.
    Explore Loan Options: Compare FHA, VA, USDA, KHC, and Conventional loans.
    Find Down Payment Assistance: Ask about programs like KHC’s assistance or grants.
    Work with a Trusted Mortgage Broker: Consider partnering with someone like Joel Lobb, a Kentucky-based mortgage expert specializing in first-time buyer programs.
    Conclusion
    Buying your first home in Kentucky doesn’t have to be intimidating. With programs like FHA, VA, USDA, and KHC, you can find a loan that fits your financial situation and homeownership goals.
    Take the first step today by getting pre-approved, exploring your options, and partnering with a knowledgeable mortgage expert.
    For more details or assistance, feel free to reach out to a trusted loan officer like Joel Lobb to guide you every step of the way.


1 –  Email – kentuckyloan@gmail.com 
2.   Call/Text – 502-905-3708

Joel Lobb
Mortgage Loan Officer – Expert on Kentucky Mortgage Loans


🌐 Website: www.mylouisvillekentuckymortgage.com
🏢 Address: 10602 Timberwood Cir, Ste 3, Louisville, KY 40223

Evo Mortgage
Company NMLS# 1738461
Personal NMLS# 57916

For assistance with Kentucky mortgage loans, reach out via email, call, or text Joel Lobb directly.

Future Ineligible map for Kentucky USDA Properties in Georgetown Kentucky

USDA Rural Development Kentucky

Notice of changes to eligible area maps for USDA Rural Development housing programs

USDA Rural Development has completed its 2020 decennial United States census review for all areas under its jurisdiction to identify areas that no longer qualify as rural for Kentucky USDA Rural Housing programs. 

Based on the review of the areas within the state of Kentucky, using 2020 US census data, and rural area guidance located in Handbook HB-1-3550, Chapter 5, the rural eligibility designation has changed for the following areas:

Areas whose rural eligibility designations are changing from ineligible to eligible (these areas now qualify as rural for USDA Housing Programs):

  • The area/towns currently outside the city of Ashland, KY (Catlettsburg, West Fairview, Fairview, Westwood, Russell).
  • The areas/towns currently outside the city of Paducah, KY (Hendron and Farley).
  • The cities of Ashland, KY and Paducah, KY will remain ineligible.

Areas whose rural eligibility designation is changing from eligible to ineligible (these areas no longer qualify as rural for USDA Housing Programs):

  • Georgetown, KY – The city of Georgetown, KY, will no longer be eligible due to the population exceeding 35,000.

Changes become effective October 1, 2023.

Kentucky USDA Rural Housing Map for Georgetown Kentucky and Scott County Kentucky

The updated rural area map can now be viewed on our eligibility website. Users will need to click on the program, for example: “Single Family Housing Direct,” and then click on “Proposed Eligibility Areas” from the menu options.

Email ThisBlogThis!Share to TwitterShare to FacebookShare to Pinterest

Labels: Ashland, Kentucky USDA Mortgage Loans, Ky, KY Georgetown, maps for eligible USDA Loans in Kentucky, Maps for Kentucky USDA Rural Development Housing Programs, Paducah, Property eligibility USDA

Kentucky Rural Housing USDA Buydown Program

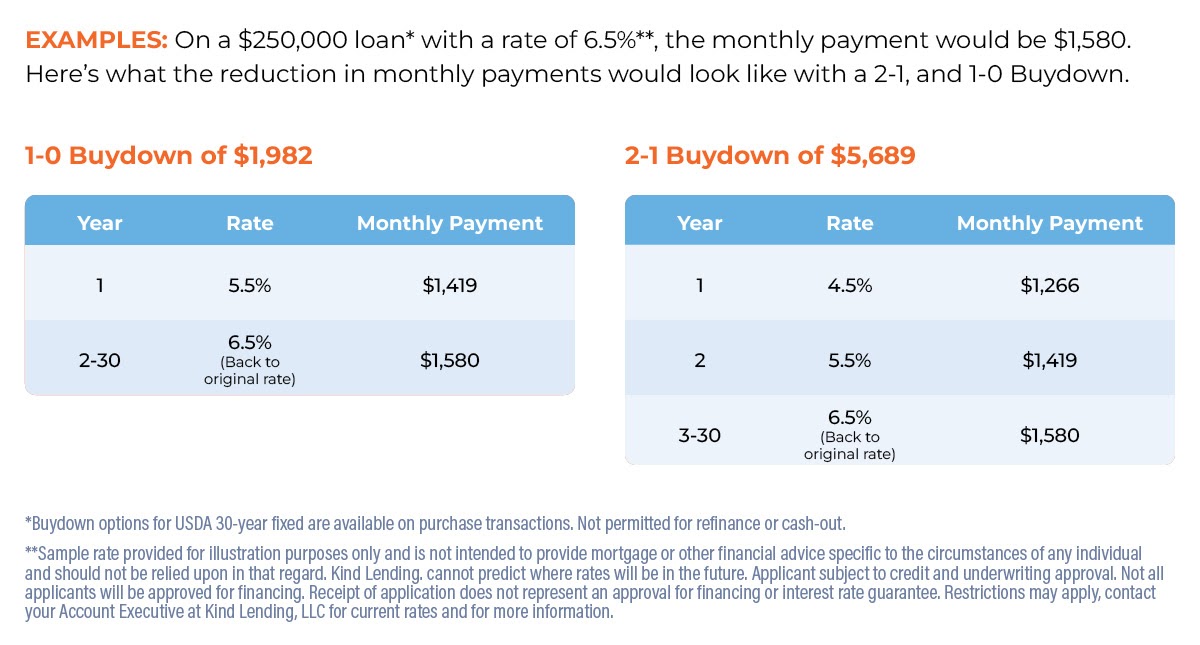
2-1 and 1-0 buydowns for Kentucky Rural Housing USDA RD loans Interest Rates.
What are Buydowns for Kentucky USDA RD Loans?

The Kentucky Rural Housing USDA Buydown Program provides simple financing options that lowers the interest rate on a mortgage for either 1 year (1-0) or 2 years (2-1), before it rises to the regular permanent rate. Specifics2-1, and 1-0 temporary interest rate buydowns are allowed on 30 year fixed-rate mortgages for principal residences, purchase only. Not permitted on refinance transactions.The seller or agent may provide funds for the temporary interest rate buydown, subject to standard interested party contribution limits.Lender paid buydowns are not offered.The borrower is qualified at the note rate fully amortized (not the buydown rate)Minimum credit score for loans with buydown is 620
2-1 and 1-0 buydowns for USDA RD loans.      What are Buydowns for USDA RD Loans?  The USDA Buydown Program at Kind Lending provides simple financing options that lowers the interest rate on a mortgage for either 1 year (1-0) or 2 years (2-1), before it rises to the regular permanent rate.    Specifics  2-1, and 1-0 temporary interest rate buydowns are allowed on 30 year fixed-rate mortgages for principal residences, purchase only. Not permitted on refinance transactions. The seller or agent may provide funds for the temporary interest rate buydown, subject to standard interested party contribution limits. Lender paid buydowns are not offered. The borrower is qualified at the note rate fully amortized (not the buydown rate) Minimum credit score for loans with buydown is 640

Have Questions or Need Expert Advice? Text, email, or call me below:

Joel Lobb
Mortgage Loan Officer

EVO Mortgage
10602 Timberwood Cir, Ste 3, Louisville, KY 40223

Text or call: 502-905-3708
email: kentuckyloan@gmail.com
NMLS #57916 | Company NMLS #1738461
www.nmlsconsumeraccess.org
Equal Housing Lender

http://www.mylouisvillekentuckymortgage.com/

The view and opinions stated on this website belong solely to the authors, and are intended for informational purposes only. The posted information does not guarantee approval, nor does it comprise full underwriting guidelines. This does not represent being part of a government agency. The views expressed on this post are mine and do not necessarily reflect the view of my employer. Not all products or services mentioned on this site may fit all people.
NMLS ID# 57916, (www.nmlsconsumeraccess.org).

Who is eligible for a Rural Housing Loan in Kentucky?

Rural Housing Loan in Kentucky

Kentucky USDA loans are loans offered by the United States Department of Agriculture to those looking to buy homes in rural areas of Kentucky.

There are a few requirements and restrictions associated with this type of loan however, if you are a first time home buyer in Kentucky with a limited income, no down payment and are looking to live in a rural part of Kentucky, this may be a good option for you to purchase a home going no money down and getting a 30 year fixed rate loan.

Income Requirements for USDA Loans in Kentucky

The Rural Housing USDA website provides an income eligibility calculator depending on where you are looking for housing in the state of Kentucky. Because it is a nationally funded loan by the United States Government, the income restrictions will vary county-by-county but the loan recipient cannot make more than 115% of the median income for the area in which they are applying. There is also a chart you can consult that provides Kentucky USDA county income limits depending on the number of people in your home. Most Kentucky counties allow up to $122,800 for a household of one to four people, and up to $162,100 for a household of five to eight. The Northern Kentucky counties of Boone, Bracken, Campbell, Gallatin, Kenton and Pendleton allow more: $128,600 for one to four people and $169,800 for five to eight. These limits took effect July 13, 2026.

Households with 1-4 members have different limits as households with 5-8. Similarly, applicants living in high-cost counties will have a higher income limit than those living in counties with a more average cost of living.

Kentucky Score Requirements for a USDA Loan in Kentucky

USDA does not publish a minimum credit score anywhere in Handbook HB-1-3555. What actually drives your file is the underwriting recommendation USDA’s automated system, GUS, gives it. A 640 middle score will typically get a GUS Accept. Below 640 the file gets manually underwritten, which is still possible. Most lenders set a 640 floor as their own overlay, but that is the lender’s rule, not a USDA rule.

If the potential borrower has declared bankruptcy or foreclosure within the last 36 months, they would be ineligible for this type of loan.

If the mortgage was included in the Bankruptcy, sometimes the 36 month hold is ignored and you just have to make sure the property is out of your name before applying for a USDA loan

Can you get a USDA loan in Kentucky with a Previous Bankruptcy?

Chapter 7 bankruptcy, the bankruptcy must have been discharged at least 3 years prior to becoming eligible for a Kentucky USDA home loan.

Borrowers must be in a Chapter 13 bankruptcy for a minimum of 12 months, with documentation of 12 months of on time payments and a letter of authorization from the bankruptcy trustee authorizing you to enter into new debt.

In order to qualify for a USDA home loan after filing a Chapter 13 bankruptcy, additional documentation may be requested/required stating that the reason for the Chapter 13 filing was due to extenuating circumstances beyond the borrower’s control, temporary in nature and not likely to re-occur.

Home must be primary Residence.

Recipients must be U.S. Citizens, U.S. non-citizen nationals or Qualified Aliens to apply for this program. They must also agree to use the home as their primary residence and not as a rental property.

The property has to be residential. That covers single family homes, townhouses, condominiums, new construction, and manufactured homes. A condo project can be approved by FHA, VA, Fannie Mae or Freddie Mac, and it does not have to already be sitting on one of those lists. It can also qualify by being shown to meet one of those agencies’ standards. An attached townhome that is not part of a condominium regime does not need any project approval at all.

What areas of Kentucky Qualify for the USDA Loan Program?

The USDA provides a map of the where you can apply a USDA loans are eligible in Kentucky. The major metro areas of Jefferson County and Fayette County Kentucky are not eligible for Rural Housing Loans in Kentucky, along with some parts of Northern Kentucky next to Cincinnati; parts of Owensboro, Paducah, Bowling Green, Richmond, Frankfort, Winchester, Radcliff, Hopkinsville and Henderson Kentucky are not eligible.

If you have a property in mind, you can head over to the eligibility map to see if the home you are considering qualifies.

What are the advantages of USDA loans in Kentucky?

For many people in a low to middle-income bracket, saving for a down payment can be difficult. A USDA loan does not require the purchaser to put any money down toward the purchase price of a home. The government insures the loan in this case, should the borrower default, therefore the borrower is required to carry mortgage insurance during the life of the loan. The mortgage insurance for the USDA loan is provided at a more discounted rate than that required by traditional loans.

On USDA loans the mortgage insurance is 1% upfront, called a guarantee fee, and .35% monthly called an annual mortgage insurance fee to USDA. The beauty of USDA, is that it does not matter if you have a credit score of 640, or a credit score of 740, everyone pays the same premiums, unlike conventional loans.

They only offer 30 year fixed rates with no prepayment penalty, and usually the rates are very low and compare to FHA rates and much lower than conventional loans.

USDA loans take on average about 30 days to close, and the appraisal must meet FHA requirements. Home inspections are not required. Manufactured homes are allowed, and since May 5, 2025 that includes existing used units, not just brand new ones off a dealer lot. An existing manufactured home has to have been built within 20 years of your closing date, sit on a permanent foundation, never have been installed at another homesite, be at least 400 square feet, still carry both the HUD certification label and the HUD data plate, and have no alterations made after it left the factory other than an engineered porch or deck.

screenshot_20201203-145606

Joel Lobb


Mortgage Loan Officer

EVO Mortgage

10602 Timberwood Cir, Ste 3

Louisville, KY 40223

NMLS #57916 | Company NMLS #1738461

Equal Housing Lender


Text/call 502-905-3708

kentuckyloan@gmail.com

If you are an individual with disabilities who needs accommodation, or you are having difficulty using our website to apply for a loan, please contact us at 502-905-3708.

Disclaimer: No statement on this site is a commitment to make a loan. Loans are subject to borrower qualifications, including income, property evaluation, sufficient equity in the home to meet Loan-to-Value requirements, and final credit approval. Approvals are subject to underwriting guidelines, interest rates, and program guidelines and are subject to change without notice based on applicant’s eligibility and market conditions. Refinancing an existing loan may result in total finance charges being higher over the life of a loan. Reduction in payments may reflect a longer loan term. Terms of any loan may be subject to payment of points and fees by the applicant Equal Opportunity Lender. NMLS#57916 http://www.nmlsconsumeraccess.org/

— Some products and services may not be available in all states. Credit and collateral are subject to approval. Terms and conditions apply. This is not a commitment to lend. Programs, rates, terms and conditions are subject to change without notice. The content in this marketing advertisement has not been approved, reviewed, sponsored or endorsed by any department or government agency. Rates are subject to change and are subject to borrower(s) qualification.