How Credit Scores Affect Your Kentucky Mortgage Loan

When you are ready to apply for a Kentucky mortgage loan approval to buy a house in the state of Kentucky, you will need a more accurate picture of how a mortgage lender may view your Transunion, Experian, Equifax credit reports and their scores. Scores go from 344 to 850 on each three credit bureaus and they take the middle score of the three, throwing out the highest and lowest score.  Kentucky Mortgage lenders look at your credit on Equifax as well as TransUnion and Experian — all 3 bureaus.

Illustration of a credit report based on Experian, TransUnion and Equifax data
 

components of Fico Score are payment history, amounts owed, credit types, new credit and length of credit

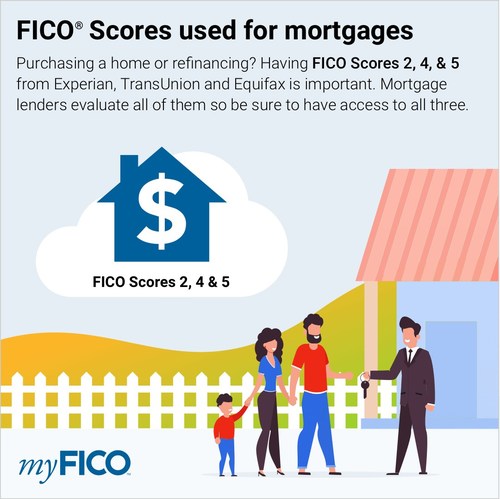
Although FICO Score version 8 is one of the latest and most predictive versions of the FICO Score, the mortgage industry generally uses the “classic” versions 5, 4 and 2 from Transunion, Equifax and Experian

Louisville Kentucky Mortgage Lender for FHA, VA, KHC, USDA and Rural  Housing Kentucky Mortgages: WHAT IS THE MINIMUM CREDIT SCORE FOR A KENTUCKY  FHA MORTGAGE HOME LOAN APPROVAL?

NapkinFinance-FICO-Napkin-08-16-20-v06


If you are planning to buy a home in Kentucky, one of the first questions you should be asking is: what credit score do I need to qualify? The second question is: what credit score do I need to get the best interest rate? These are not the same question. Qualifying is one thing. Securing optimal pricing is another.

Kentucky minimum credit score requirements by loan type

Credit score alone does not determine approval. Underwriting also evaluates income stability, debt-to-income ratio, assets, employment history, and the appraisal. That said, credit score is still a critical approval gate for most programs.

FHA loan (Federal Housing Administration)

  • Minimum allowed by HUD: 580 for 3.5% down; 500–579 typically requires 10% down
  • Real-world lender requirement in Kentucky: most lenders will not go below 580; many prefer 600–620

VA loan (Veterans Affairs)

  • VA does not publish a minimum credit score
  • Real-world lender overlays: most lenders require 580–620; stronger pricing typically starts at 640+

USDA Rural Development (guaranteed)

  • Technically, 580 may be accepted in some cases
  • In practice, 640+ is commonly needed for smoother automated approval; under 640 may trigger manual underwriting

Conventional (Fannie Mae)

  • 620 minimum
  • Best pricing is typically 740–760+

KHC (Kentucky Housing Corporation) with down payment assistance

  • 620 minimum
  • No exceptions for most KHC DPA options

Bottom line: most realistic Kentucky approval scenarios begin at 580 for FHA/VA and 620 for Conventional/KHC. USDA is often most efficient at 640+.

Government guidelines vs lender overlays

Programs like FHA, VA, USDA, Fannie Mae, and KHC publish baseline guidelines. Lenders often add overlays (stricter rules) due to risk and secondary market requirements. This is why “on paper” minimums may not match what lenders actually approve.

How lenders calculate your qualifying credit score

Mortgage lenders pull a tri-merge credit report showing three scores from Equifax, Experian, and TransUnion. The lender discards the highest and lowest score and uses the middle score.

Example:

  • Equifax: 610
  • Experian: 629
  • TransUnion: 614

Your qualifying score would be 614 (the middle score).

Most lenders require at least two usable scores. Also, the score you see on consumer apps is often not the same score model used for mortgage underwriting.

What credit score typically gets the best interest rate?

Rate pricing improves as scores rise. While exact pricing varies by day, lender, and loan type, these tiers are common:

  • 620–639: higher rates and limited pricing
  • 640–679: improved options
  • 680–719: strong approval tier
  • 720–759: excellent pricing
  • 760+: top tier pricing

If you are within 10–20 points of a better tier, improving your score before you lock can materially reduce your payment and long-term interest cost.

If your credit score is low: what to do next

Do not guess. Do not apply randomly. Also, do not dispute accounts without a plan (disputes can delay underwriting). The most effective approach is a structured credit review focused on:

  • reducing revolving utilization
  • verifying tradeline reporting accuracy
  • strategic payoff sequencing if needed
  • avoiding new inquiries and new debt

In many cases, meaningful improvement can happen in 30–60 days with the right steps.

Images from the original post

Replace the image URLs below with your WordPress Media Library URLs (or paste your existing image blocks here).

Credit score tiers for Kentucky mortgage approvals
Tri-merge credit report middle score example
Tri-merge credit report: how the middle score is used
Credit score range impact on mortgage rates
How credit score ranges can affect mortgage pricing

Frequently asked questions

What is the minimum credit score to buy a home in Kentucky?

Many lenders will consider FHA/VA at 580+ and Conventional/KHC at 620+. USDA is commonly easiest at 640+ for automated approval, though exceptions may exist depending on the full file.

Does VA have a minimum credit score requirement?

VA does not publish a minimum credit score. However, most lenders use overlays and commonly require 580–620.

Why is my Credit Karma score different than my mortgage score?

Mortgage lending uses specific FICO score models. Many consumer apps show different scoring models intended for education and monitoring, not mortgage underwriting.

How do lenders pick which credit score they use?

With three bureau scores, lenders typically use the middle score (not the highest or the lowest). Most lenders also require at least two usable scores.

What score gets the best mortgage rate?

Top pricing is commonly seen at 760+ and often strong pricing begins around 740+. Exact pricing depends on the loan type, down payment, DTI, reserves, and market conditions.

Contact

Joel Lobb
Senior Loan Officer
NMLS #57916
Website: http://mylouisvillekentuckymortgage.com/
Text or call: (502) 905-3708
Email: kentuckyloan@gmail.com


The views and opinions stated on this website belong solely to the author and are intended for informational purposes only. Posted information does not guarantee approval and does not represent full underwriting guidelines. This does not represent being part of a government agency. The views expressed do not necessarily reflect the view of my employer. Not all products or services mentioned may fit all borrowers. NMLS ID #57916 (www.nmlsconsumeraccess.org). USDA mortgage loans only offered in Kentucky.

All loans and lines are subject to credit approval, verification, and collateral evaluation and are originated by lender. Products and interest rates are subject to change without notice.

{ “@context”: “https://schema.org”, “@type”: “FAQPage”, “mainEntity”: [ { “@type”: “Question”, “name”: “What is the minimum credit score to buy a home in Kentucky?”, “acceptedAnswer”: { “@type”: “Answer”, “text”: “Many lenders will consider FHA/VA at 580+ and Conventional/KHC at 620+. USDA is commonly easiest at 640+ for automated approval, though exceptions may exist depending on the full file.” } }, { “@type”: “Question”, “name”: “Does VA have a minimum credit score requirement?”, “acceptedAnswer”: { “@type”: “Answer”, “text”: “VA does not publish a minimum credit score. However, most lenders use overlays and commonly require 580–620.” } }, { “@type”: “Question”, “name”: “Why is my Credit Karma score different than my mortgage score?”, “acceptedAnswer”: { “@type”: “Answer”, “text”: “Mortgage lending uses specific FICO score models. Many consumer apps show different scoring models intended for education and monitoring, not mortgage underwriting.” } }, { “@type”: “Question”, “name”: “How do lenders pick which credit score they use?”, “acceptedAnswer”: { “@type”: “Answer”, “text”: “With three bureau scores, lenders typically use the middle score (not the highest or the lowest). Most lenders also require at least two usable scores.” } }, { “@type”: “Question”, “name”: “What score gets the best mortgage rate?”, “acceptedAnswer”: { “@type”: “Answer”, “text”: “Top pricing is commonly seen at 760+ and often strong pricing begins around 740+. Exact pricing depends on the loan type, down payment, DTI, reserves, and market conditions.” } } ] } { “@context”: “https://schema.org”, “@type”: “MortgageLoan”, “name”: “Kentucky Mortgage Loan Options: FHA, VA, USDA, Conventional, KHC”, “description”: “Educational overview of credit score requirements and typical lender overlays for Kentucky mortgage loans, including FHA, VA, USDA, Conventional (Fannie Mae), and KHC down payment assistance options.”, “loanType”: [“FHA”, “VA”, “USDA”, “Conventional”, “KHC”], “areaServed”: { “@type”: “State”, “name”: “Kentucky” }, “provider”: { “@type”: “MortgageBroker”, “name”: “Joel Lobb, Mortgage Broker FHA, VA, KHC, USDA”, “telephone”: “+1-502-905-3708”, “email”: “kentuckyloan@gmail.com”, “url”: “http://mylouisvillekentuckymortgage.com/”, “identifier”: { “@type”: “PropertyValue”, “name”: “NMLS”, “value”: “57916” } }, “isBasedOn”: “Credit score guidance varies by program and lender overlays. Final approval depends on full underwriting including income, assets, DTI, and appraisal.”, “disclaimer”: “Informational only. Not a commitment to lend. All loans subject to credit approval, verification, and collateral evaluation. Rates and programs subject to change.” }

USDA Appraisal Requirements and Home Inspection Checklist (2026)

Kentucky USDA Loan Guide · Updated September 2026

A USDA appraisal does two jobs: it confirms the home is worth the price, and it confirms the home meets HUD’s minimum property standards. Use the checklist below before you make an offer and again before the appraiser arrives, so repairs don’t push back your closing.

USDA appraisal requirements at a glance

  • Standard: the home must meet HUD Handbook 4000.1 minimum property standards: safe, sound and sanitary.
  • Appraiser: licensed or certified in Kentucky and familiar with HUD 4000.1. The appraiser certifies on the report that the home meets those standards.
  • Validity: the appraisal must be completed within 180 days of closing. Older appraisals can be updated.
  • Repairs: anything the appraiser flags must be fixed and re-inspected, or handled through a repair escrow if the lender allows it.
  • Home inspection: not required by USDA, but strongly recommended.

Source: USDA HB-1-3555, Chapter 12 (Property and Appraisal Requirements).

How the USDA appraisal works

  1. Your lender orders the appraisal after the purchase contract is signed.
  2. The appraiser inspects the home, pulls comparable sales and determines market value.
  3. If the home has deficiencies, the report is issued “subject to” repairs.
  4. The repairs are completed, usually by the seller, and the appraiser re-inspects.
  5. The appraiser signs off, and the file moves on to underwriting and USDA review.

USDA appraisal and inspection checklist

Walk the house with this list. Anything you can’t check off is a likely repair item.

Safety and access

  • ☐ Handrails on interior and exterior stairways
  • ☐ Guardrails on decks, porches and landings that need them
  • ☐ No exposed wiring; junction boxes covered
  • ☐ Every bedroom has a window or door that opens to the outside
  • ☐ Year-round vehicle access to the home
  • ☐ No nearby hazards (leaking tanks, contamination, high-voltage lines over the house)

Exterior and roof

  • ☐ Roof keeps water out, with no active leaks or missing shingles
  • ☐ Siding intact, no holes or rot
  • ☐ No chipped or peeling paint on homes built before 1978
  • ☐ Gutters, chimney, steps and porches sound
  • ☐ Foundation free of major cracks or settling
  • ☐ Pool (if any) meets local safety code

Systems and utilities

  • ☐ All utilities on for the appraisal: water, electric, gas and heat
  • ☐ Heating system works and heats the living area
  • ☐ Water heater works, with a proper relief valve
  • ☐ Electrical panel safe, with working outlets and lights in every room
  • ☐ No active plumbing leaks

Kitchen and baths

  • ☐ Working sink with hot and cold water
  • ☐ Appliances that convey with the sale are working
  • ☐ Toilets, tubs and showers work without leaks
  • ☐ Bathrooms vented (exhaust fan or window)

Crawl space and basement

  • ☐ No standing water or active moisture
  • ☐ Crawl space accessible for the appraiser
  • ☐ No visible wood rot, damaged joists or insect damage

Before the appraiser arrives

  • ☐ Utilities confirmed on (vacant and foreclosed homes)
  • ☐ Attic and crawl space accessible
  • ☐ Obvious small repairs done: paint, handrails, outlet covers
  • ☐ Well water test ordered, if the home has a well

Well and septic requirements for USDA loans

Many rural Kentucky homes have a private well or septic system. USDA’s rules:

  • Well water test: performed by the local health department or a state-certified lab. The water must meet state or local standards, or EPA limits where no local standard exists. The test report can be no more than 180 days old at closing.
  • Well location: the well should be on the property. A well on a neighbor’s land needs recorded water rights and a maintenance agreement.
  • Well-to-septic distance: must meet HUD 4000.1 or be approved by the local or state health authority.
  • Septic: if a qualified appraiser certifies the home meets HUD standards, no separate septic certification is required. The system must show no evidence of failure and must sit entirely on the property, or have a recorded easement.
  • Shared wells: allowed only when public water isn’t feasible, and they need a continuous, safe supply plus a shared-well agreement.

Is a termite inspection required for a USDA loan?

Only when the lender, the appraiser, a home inspector or state law requires one. It’s most often triggered when the appraiser sees signs of damage. Many lenders order one on existing homes anyway, so ask early and budget roughly $75 to $150 for it.

USDA appraisal vs. home inspection

USDA appraisalHome inspection
Required?YesNo, but recommended
Who it protectsThe lender and USDAYou, the buyer
What it checksValue, plus visible health and safety issuesDetailed condition of roof, systems, structure and components
Can require repairs?YesNo, but its findings help you negotiate

Your lender must give you HUD’s For Your Protection: Get a Home Inspection notice. Take the advice: the appraisal is not a full inspection.

What if the home needs repairs?

Most repairs are completed before closing and re-inspected by the appraiser. USDA also allows a repair escrow in limited cases:

  • The home must be livable at closing.
  • The unfinished work must be minor, or delayed by weather, and cost no more than 10% of the loan amount.
  • Repairs must be finished within 180 days of closing. Exterior work delayed by weather can be extended to 240 days.

Not every lender offers repair escrows. If you think the home needs work, tell me before you write the offer.

How long does a USDA appraisal take in Kentucky?

Plan on about one to two weeks from order to report, and longer in some rural counties or when the appraiser needs to come back to re-inspect repairs. The appraisal is only one step. See how long a Kentucky USDA loan takes to close for the full timeline, and check today’s USDA turn times for the current USDA review queue.

USDA appraisal FAQs

Does USDA use the same appraisal standards as FHA?

Yes. USDA uses HUD Handbook 4000.1 minimum property standards, the same standards used for FHA.

Who pays for the USDA appraisal?

The buyer typically pays it upfront or at closing. Sellers can pay closing costs as part of the contract.

What happens if the appraisal comes in low?

You can renegotiate the price, bring cash to cover the gap, or cancel if your contract has an appraisal contingency. (When the appraisal comes in above the price, USDA can finance closing costs up to the appraised value.)

How long is a USDA appraisal good for?

It must be completed within 180 days of closing. An older appraisal can be updated rather than redone.

Joel Lobb, Mortgage Loan Officer, NMLS #57916 | EVO Mortgage, Company NMLS #1738461. Equal Housing Lender. Call or text 502-905-3708.

This content is for educational purposes only and is not a commitment to lend. Loan approval is subject to credit, underwriting, property and program guidelines. Not affiliated with USDA or any government agency.

Kentucky USDA Home Loan Guide: Qualifying Criteria Explained

The Kentucky Rural Housing  USDA home loan program offers an excellent opportunity for eligible homebuyers in rural and suburban areas of Kentucky to secure affordable financing with no down payment. To qualify, applicants must meet specific requirements related to credit score, income, work history, bankruptcy, foreclosure, debt-to-income ratio, property requirements, and mortgage insurance. Here’s a detailed guide to help you understand these qualifications:

Credit Score Required For Kentucky Rural Housing Approval

No minimum credit score but a 580 to  640 is generally required to qualify for a USDA loan. This score allows for streamlined processing through the Guaranteed Underwriting System (GUS). Applicants with scores below 640 may still qualify but will need to undergo manual underwriting, which requires additional documentation and scrutiny.

Income Requirements for Kentucky USDA Rural Housing Approval

USDA loans have income limits that vary by county and household size. These limits are designed to ensure the program assists low- to moderate-income families. Generally, your household income should not exceed 115% of the median income for your area. The USDA provides an online tool to check income eligibility based on your location and household size.

Work History requirements for Kentucky USDA loan Approval 

A stable work history is essential for Kentucky  USDA loan approval. Lenders typically look for at least two years of consistent employment. Any gaps in employment need to be explained and documented. For self-employed applicants, a minimum of two years of tax returns is required to verify income stability.

Kentucky USDA Rural Housing Bankruptcy and Foreclosure Guidelines

While past financial difficulties like bankruptcy or foreclosure can affect your eligibility, they do not automatically disqualify you. Here are the typical waiting periods:

  • Chapter 7 Bankruptcy: At least three years from the discharge date.
  • Chapter 13 Bankruptcy: At least one year of the payout period must be completed with satisfactory payment history and court approval for a new loan.
  • Foreclosure: At least three years from the completion date.

Kentucky USDA Debt-to-Income Ratio (DTI) Requirements

The Kentucky USDA loan program has specific DTI requirements to ensure borrowers can manage their mortgage payments. The front-end ratio (housing expenses) should not exceed 29% of your gross monthly income, and the back-end ratio (total monthly debt obligations) should not exceed 45%. Exceptions can be made for borrowers with compensating factors, such as higher credit scores or additional cash reserves.

Kentucky USDA Property Requirements

USDA loans are intended for properties in designated rural areas. The USDA provides an online tool to check property eligibility. The home must be used as the primary residence and meet certain quality standards according to Kentucky FHA Appraisal HUD Guidelines  including:

  • Adequate and functional heating, plumbing, and electrical systems
  • Structurally sound foundation and roof
  • Safe water supply and waste disposal systems
  • Must have an undamaged exterior, foundation and roof
  • Must have safe and reasonable property access
  • Must not contain loose wiring and exposed electrical systems
  • Must have all relevant utilities, including gas, electricity, water and sewage functioning properly.
  • Must have a working, permanent heating system that can heat the property adequately
  • Must have surfaces free of chipping or peeling lead-based paint
  • Must have adequate access to attic spaces and natural ventilation in crawl spaces
  • Must have access to potable water
  • Must be free from wood-destroying insect infestations
  • Must not have interior and exterior health and safety hazards, such as no handrails on steep staircases
  • Must be a marketable property

Mortgage Insurance Required For Kentucky USDA loan Approval

Kentucky Rural Housing USDA loans require mortgage insurance, which includes an upfront guarantee fee and an annual fee. The upfront fee is typically 1% of the loan amount, which can be financed into the loan. The annual fee, usually 0.35% of the loan balance, is paid monthly as part of the mortgage payment. These fees help protect lenders and the USDA in case of borrower default.


Qualifying for a USDA home loan in Kentucky involves meeting specific criteria in several areas: Credit Score: No Minimum score but a 620-640 for streamlined processing; lower scores may require manual underwriting down to 580 with some lenders but few and far between Income Requirements: Must not exceed 115% of the median income for your area. Work History: At least two years of stable employment. Bankruptcy and Foreclosure: Waiting periods of 1-3 years depending on the situation. Debt-to-Income Ratio: 29% for housing expenses, 41% for total debt; exceptions possible. Property Requirements: Must be in a designated rural area and meet quality standards. Mortgage Insurance: Includes an upfront guarantee fee and an annual

Summary

Qualifying for a USDA home loan in Kentucky involves meeting specific criteria in several areas:

  • Credit Score: No Minimum score but a 620-640 for streamlined processing; lower scores may require manual underwriting down to 580 with some lenders but few and far between
  • Income Requirements: Must not exceed 115% of the median income for your area.
  • Work History: At least two years of stable employment.
  • Bankruptcy and Foreclosure: Waiting periods of 1-3 years depending on the situation.
  • Debt-to-Income Ratio: 29% for housing expenses, 41% for total debt; exceptions possible.
  • Property Requirements: Must be in a designated rural area and meet quality standards.
  • Mortgage Insurance: Includes an upfront guarantee fee and an annual fee.

By understanding and meeting these requirements, you can take advantage of the USDA loan program to achieve homeownership in Kentucky’s rural areas. For personalized assistance, consider consulting with a mortgage broker or lender experienced in USDA loans, like Joel Lobb in Louisville, who can guide you through the process and help you qualify.

Joel Lobb
Mortgage Broker – FHA, VA, USDA, KHC, Fannie Mae
EVO Mortgage • Helping Kentucky Homebuyers Since 2001
📞 Call/Text: 502-905-3708
📧 Email: kentuckyloan@gmail.com
🌐 Website: www.mylouisvillekentuckymortgage.com
🏠 Address: 10602 Timberwood Cir, Ste 3, Louisville, KY 40223
NMLS #57916 | Company NMLS #1738461
Free Info & Homebuyer Advice →
Kentucky Mortgage Loan Expert
FHA | VA | USDA | KHC Down Payment Assistance | Fannie Mae
Equal Housing Lender. This is not a commitment to lend. All loans are subject to credit approval and program requirements.

Kentucky Mortgage Underwriting: Key Guidelines Explained

Understanding Kentucky Mortgage underwriting guidelines

All lending institutions have different Underwriting Guidelines set in place when reviewing a borrower’s financial history to determine the likelihood of receiving on-time payments. The primary items reviewed are the following 5 areas below:

1. Income

2. Debt

3. Credit History

4. Savings

5. Debt vs Income Ratio


Income

Income is one of the most important variables a lender will examine because it is used to repay the loan. Income is reviewed for the type of work, length of employment, educational training required, and opportunity for advancement. An underwriter will look at the source of income and the likelihood of its continuance to arrive at a gross monthly figure.

Salary and Hourly Wages – Calculated on a gross monthly basis, prior to income tax deductions.

Part-time and Second Job Income – Not usually considered unless it is in place for 12 to 24 straight months. Lenders view part-time income as a strong compensating factor.

Commission, Bonus and Overtime Income – Can only be used if received for two previous years. Further, an employer must verify that it is likely to continue. A 24-month average figure is used.

Retirement and Social Security Income – Must continue for at least three years into the future to be considered. If it is tax free, it can be grossed up to an equivalent gross monthly figure. Multiply the net amount by 1.20%.

Alimony and Child Support Income – Must be received for the 12 previous months and continue for the next 36 months. Lenders will require a divorce decree and a court printout to verify on-time payments.

Notes Receivable, Interest, Dividend and Trust Income – Proof of receiving funds for 12 previous months is required. Documentation showing income due for 3 more years is also necessary. Rental Income – Cannot come from a Primary Residence roommate. The only acceptable source is from an investment property. A lender will use 75% of the monthly rent and subtract ownership expenses. The Schedule E of a tax return is used to verify the figures. If a home rented recently, a copy of a current month-to-month lease is acceptable.

Automobile Allowance and Expense Account Reimbursements – Verified with 2 years tax returns and reduced by actual expenses listed on the income tax return Schedule C.

Education Expense Reimbursements – Not considered income. Only viewed as slight compensating factor.

Self-Employment Income – Lenders are very careful in reviewing self-employed borrowers. Two years minimum ownership is necessary because two years is considered a representative sample. Lenders use a 2-year average monthly income figure from the Adjusted Gross Income on the tax returns. A lender may also add back additional income for depreciation and one-time capital expenses. Self-employed borrowers often have difficulty qualifying for a mortgage due to large expense write offs. A good solution to this challenge used to be the No Income Verification Loan, but there are very few of these available any more given the tightened lending standards in the current economy. NIV loan programs can be studied in the Mortgage Program section of the library.

2. Debt

An applicant’s liabilities are reviewed for cash flow. Lenders need to make sure there is enough income for the proposed mortgage payment, after other revolving and installment debts are paid.

All loans, leases, and credit cards are factored into the debt calculation. Utilities, insurance, food, clothing, schooling, etc. are not.

If a loan has less than 10 months remaining, a lender will usually disregard it.

The minimum monthly payment listed on a credit card bill is the figure used, not the payment made.

An applicant who co-borrowed for a friend or relative is accountable for the payment. If the applicant can show 12 months of on-time cancelled checks from the co-borrower, the debt will not count.

Loans can be paid off to qualify for a mortgage, but credit cards sometimes cannot (varies by lender). The reasoning is that if the credit card is paid off, the credit line still exists, and the borrower can run up debt after the loan is closed.

A borrower with fewer liabilities is thought to demonstrate superior cash management skills.

Credit History


Most lenders require a residential merged credit report (RMCR) from the 3 main credit bureaus: Trans Union, Equifax, and Experian. They will order one report which is a blending of all three credit bureaus and is easier to read than the individual reports. This “blended” credit report also searches public records for liens, judgments, bankruptcies and foreclosures. See our credit report index.Credit report in hand, an underwriter studies the applicant’s credit to determine the likelihood of receiving an on-time mortgage payment. Many studies have shown that past performance is a reflection of future expectations. Hence, most lenders now use a national credit scoring system, typically the FICO score, to evaluate credit risk. If you’re worried about credit scoring, see our articles on it.

The mortgage lending process, once very forgiving, has tightened lending standards considerably. A person with excellent credit, good stability, and sufficient documentable income to make the payments comfortably will usually qualify for an “A” paper loan. “A Paper”, or conforming loans, make up the majority of loans in the U.S. and are loans that must conform to the guidelines set by Fannie Mae or Freddie Mac in order to be saleable by the lender. Such loans must meet established and strict requirements regarding maximum loan amount, down payment amount, borrower income and credit requirements and suitable properties. Loans that do not meet the credit and/or income requirements of conforming “A-paper” loans are known as non-conforming loans and are often referred to as “B”, “C” and “D” paper loans depending on the borrower’s credit history and financial capacity.

Here are some rules of thumb most lenders follow:

12 plus months positive credit will usually equal an A paper loan program, depending on the overall credit. FHA loans usually follow this guideline more often than conventional loans.

Unpaid collections, judgments and charge offs must be paid prior to closing an A paper loan. The only exception is if the debt was due to the death of a primary wage earner, or the bill was a medical expense.

If a borrower has negotiated an acceptable payment plan and has made on time payments for 6 to 12 months, a lender may not require a debt to be paid off prior to closing.

Credit items usually are reported for 7 years. Bankruptcies expire after 10 years.

Foreclosure – 5 years from the completion date. From the fifth to seventh year following the foreclosure completion date, the purchase of a principal residence is permitted with a minimum 10% down and 680 FICO score. The purchase of a second or investment property is not permitted for 7 years. Limited cash out refinances are permitted for all occupancy types.

Pre-foreclosure (Short Sale) – 2 years from the completion date (no exceptions or extenuating circumstances).

Deed-in-Lieu of Foreclosure – 4-year period from the date the deed-in-lieu is executed. From the fifth to the seventh year following the execution date the borrower may purchase a property secured by a principal residence, second home or investment property with the greater of 10 percent minimum down payment or the minimum down payment required for the transaction. Limited cash out and cash out refinance transactions secured by a principal residence, second home or investment property are permitted pursuant to the eligibility requirements in effect at that time.

Chapter 7 Bankruptcy – A borrower is eligible for an A paper loan program 4 years after discharge or dismissal, provided they have reestablished credit and have maintained perfect credit after the bankruptcy.

Chapter 13 Bankruptcy – 2 years from the discharge date or 4 years from the dismissal date.

Multiple Bankruptcies- 5 years from the most recent dismissal or discharge date for borrowers with more than one filing in the past 7 years.

The good credit of a co-borrower does not offset the bad credit of a borrower.

Credit scores usually range from 400 to 800. Changes to lending standards are occurring on a daily basis as a result of tightening lending standards and can vary from lender-to-lender– so this information should be considered simply a guideline. For conforming loans, most lenders will lend down to a FICO of 620, with additional rate hits for the lower-end credit scores and loan-to-values. When you are borrowing more than 80%, they typically will not lend if you have a FICO below 680. The FHA/VA program just changed their minimum required FICO to 620, unless you are qualifying a borrower with non-traditional credit. The few non-conforming loan programs that are still available typically require 30% down payment with a minimum FICO of 700 for self-employed and 650 for W-2 employees, and the loan-to-value will change with the loan amount.

Lenders evaluate savings for three reasons.

The more money a borrower has after closing, the greater the probability of on-time payments.

Most loan programs require a minimum borrower contribution.

Lenders want to know that people have invested their own into the house, making it less likely that they will walk away from their life’s savings. They analyze savings documents to insure the applicant did not borrow the funds or receive a gift.

Lenders look at the following types of accounts and assets for down payment funds:

Checking and Savings – 90 days seasoning in a bank account is required for these funds. Gifts and Grants – After a borrower’s minimum contribution, a gifts or grant is permitted.

Sale of Assets – Personal property can be sold for the required contribution. The property should be appraised, and a bill of sale is required. Also, a copy of the received check and a deposit slip are needed.

Secured Loans – A loan secured by property is also an acceptable source of closing funds.

IRA, 401K, Keogh & SEP – Any amount that can be accessed is an acceptable source of funds.
Sweat Equity and Cash On Hand – Generally not acceptable. FHA programs allow it in special circumstances.
Sale Of Previous Home – Must close prior to new home for the funds to be used. A lender will ask for a listing contract, sales contract, or HUD 1 closing statement.

The percentage of one’s debt to income is one of the most important factors when underwriting a loan. Lenders have determined that a house payment should not exceed approximately 30% of Gross Monthly Income. Gross Monthly Income is income before taxes are taken out. Furthermore, a house payment plus minimum monthly revolving and installment debt should be less than 40% of Gross Monthly Income (this figure varies from 35%-41% contingent on the source of financing).

Example

An applicant has $4,500 gross monthly income. The maximum mortgage payment is:

$4500 X .30 = $1350

Their total debts come to:

$500 Car

$20 Visa

$30 Sears

$75 Master Card

—————-

$625 per month.

Remember, their total debts (mortgage plus other debts) must be less than or equal to 40% of their gross monthly income.

$2,800 X .40 = $1800

$1800 is the maximum debt the borrower can have, debts and mortgage payments combined. Can the borrower keep all their debts and have the maximum mortgage payment allowed? NO!

In this case, the borrower, since they have high debts, must adjust the maximum mortgage payment downward, because:

$625 debts

$1350 mortgage
————-

$1975 – which is more than the $1800 (40% of gross debt) we calculated above.

The maximum mortgage payment is therefore:

$1800 – $625 (monthly debt) = $1175.

Some restrictions apply. Ask for details. Loan decision is subject to satisfactory appraisal and title review and no change in financial condition. This is not an offer for extension of credit or a commitment to lend. Equal Housing Opportunity.
This communication is provided to you for informational purposes only and should not be relied upon by you.
Joel Lobb
Mortgage Broker – FHA, VA, USDA, KHC, Fannie Mae
EVO Mortgage • Helping Kentucky Homebuyers Since 2001
📞 Call/Text: 502-905-3708
📧 Email: kentuckyloan@gmail.com
🌐 Website: www.mylouisvillekentuckymortgage.com
🏠 Address: 10602 Timberwood Cir, Ste 3, Louisville, KY 40223
NMLS #57916 | Company NMLS #1738461
Free Info & Homebuyer Advice →
Kentucky Mortgage Loan Expert
FHA | VA | USDA | KHC Down Payment Assistance | Fannie Mae
Equal Housing Lender. This is not a commitment to lend. All loans are subject to credit approval and program requirements.
Disclaimer: No statement on this site is a commitment to make a loan. Loans are subject to borrower qualifications, including income, property evaluation, sufficient equity in the home to meet Loan-to-Value requirements, and final credit approval. Approvals are subject to underwriting guidelines, interest rates, and program guidelines and are subject to change without notice based on applicant’s eligibility and market conditions. Refinancing an existing loan may result in total finance charges being higher over the life of a loan. Reduction in payments may reflect a longer loan term. Terms of any loan may be subject to payment of points and fees by the applicant  Equal Opportunity Lender. NMLS#57916http://www.nmlsconsumeraccess.org/
How to Get Approved for a USDA Mortgage Loan in Kentucky

Kentucky USDA Mortgage Loan Guide

Your Complete Roadmap to Zero-Down Financing in 2026

What Is a USDA Mortgage Loan?

The USDA Rural Development Guaranteed Loan Program is designed to help Kentucky families purchase homes in eligible rural areas. With over 20 years of experience assisting more than 1,300 Kentucky families, I’ve successfully guided hundreds through USDA loans across all 120 counties.

✓ 100% financing (zero down payment)
✓ Below-market fixed interest rates
✓ Flexible credit requirements
✓ Low mortgage insurance (0.35%)
✓ Financing of closing costs possible
✓ Seller concessions allowed

If you’re a first-time homebuyer looking for a true no-money-down option without VA benefits, USDA is your strongest choice.

Property Eligibility

The property must be located in a USDA-eligible rural zone. The excellent news for Kentucky buyers: most of the state qualifies. While Louisville and Lexington city centers are ineligible, surrounding suburban areas typically qualify.

Typically Eligible Areas

  • Most of Hardin, Meade, Breckenridge, Grayson, Nelson, Spencer, and Shelby Counties
  • Large portions of Bullitt County outside immediate Louisville limits
  • Nearly all of Eastern and Western Kentucky
  • Suburban pockets around Lexington, Georgetown, Winchester, and Nicholasville
Check Eligibility: Use the USDA property eligibility map to verify any address before making an offer. This step saves time and ensures you’re pursuing viable properties.

Income Limits for 2026

Your total household income must not exceed the USDA county limit for your family size. USDA counts all household income, including spouses, adult children, part-time earnings, and bonuses.

Household Size 2026 Income Limit Range
1–4 People Up to approximately $119,850 for 1-4 members and $158,250 for 5-8 members
5–8 People Up to approximately $ $119,850 for 1-4 members and $158,250 for 5-8 members

Note: Limits vary by county. Contact me for your specific county’s limits.

Credit Score Requirements

While USDA doesn’t publish a minimum credit score, Kentucky lenders follow these general guidelines:

640+ Credit Score — Easiest Path to Approval

  • Eligible for automated approval through GUS (USDA’s system)
  • More flexible debt-to-income ratios
  • Faster underwriting timeline

580–639 — Possible With Manual Underwriting

Approvals in this range require strong supporting documentation:

  • Perfect rental history
  • No late payments in the past 12 months
  • Low overall debt
  • Stable employment history

Below 580 — Case-by-Case Review

Not impossible, but uncommon. Success requires significant compensating factors and strong manual underwriting review.

Employment Rules

Underwriters typically require a 2-year work history, though it doesn’t need to be at the same job. USDA is flexible about career transitions within reason.

USDA Accepts

  • Job changes within the same field or industry
  • Recent graduates working in their trained field
  • 12+ months of consistent income
  • Self-employed borrowers (with 2 years of tax returns)

Red Flags to Avoid

  • Job gaps longer than 60 days
  • Declining income trends over time
  • Multiple unrelated job switches

Debt-to-Income Ratio Requirements

Your DTI is calculated as a percentage of your gross monthly income.

DTI Type Standard Limit With Strong Credit (GUS Approve)
Front-End (Housing Only) 29% Up to 29–34%
Back-End (All Debt) 41% 44%+

Manual underwriting files must stay closer to standard limits, while automated approvals offer more flexibility.

Bankruptcy & Foreclosure Waiting Periods

If you’ve experienced financial hardship, USDA has established waiting periods before approval:

Credit Event Waiting Period
Chapter 7 Bankruptcy 3 Years from Discharge
Chapter 13 Bankruptcy 12 Months of On-Time Payments + Trustee Approval
Foreclosure 3 Years from Sale Date
Short Sale 3 Years (Typical)
Medical collections and older accounts rarely require payoff. Your individual circumstances matter—let’s review your specific situation.

Property Condition & Appraisal Requirements

Your home must be safe, sound, and sanitary. The USDA appraiser evaluates:

  • Roof condition and remaining lifespan
  • Foundation stability and integrity
  • Electrical system safety
  • Plumbing functionality
  • Adequate heating system for the entire home
  • Absence of active termite damage
  • No peeling lead-based paint

Most repairs can be handled by the seller before closing. This is a negotiation point in your offer.

The USDA Loan Process

1Pre-Qualification

Credit check, income estimate, DTI calculation, and review of eligible areas

2Full Pre-Approval

Gather pay stubs, W-2s, tax returns, bank statements, and photo ID

3Find Your Home

Use eligibility maps to confirm the property qualifies before making an offer

4Loan Application & Underwriting

Rate lock, appraisal order, document review, and GUS findings

5USDA Final Approval

Conditional Commitment issued (typically 2–7 days)

6Closing Day

Sign final paperwork, receive keys, and move into your new home

Timeline: Most Kentucky USDA loans close within 30–45 days from application.

Frequently Asked Questions

Do I need a down payment?

No—USDA loans provide 100% financing with zero down payment required.

Can I buy in Louisville or Lexington?

City centers are ineligible, but many surrounding suburbs qualify. Always verify the property address on the USDA eligibility map before making an offer.

What credit score do I need?

640+ is ideal for streamlined approval. Manual underwriting may consider scores down to 580 with strong compensating factors.

Can the seller help with closing costs?

Yes—USDA allows seller concessions, and some closing costs can be financed if the appraisal supports it.

How long does the process take?

Most Kentucky USDA loans close in 30–45 days from application.

Are there down payment assistance programs?

Yes. Kentucky Housing Corporation (KHC) programs offer additional assistance for qualified first-time homebuyers to further reduce upfront costs.

Ready to Get Pre-Approved?

Let’s explore your USDA lending options with personalized guidance and same-day approvals.

Call or Text: 502-905-3708
Email: kentuckyloan@gmail.com

Serving qualified homebuyers across all 120 Kentucky counties

Joel Lobb, Mortgage Loan Officer | Specialist in Kentucky FHA, VA, USDA, KHC & Fannie Mae Loans

EVO Mortgage — Helping Kentucky Homebuyers Since 2001

NMLS Personal ID: 57916 | Company NMLS ID: 1738461 | Equal Housing Lender

This website is not endorsed by the USDA, FHA, VA, or any government agency. It is an independent educational resource.

This is not a commitment to lend. All loans subject to credit approval and USDA program guidelines.