Qualifications for a USDA Loan to Buy a Home in Kentucky
Purchasing a home in Kentucky can be made more accessible through the United States Department of Agriculture (USDA) Loan Program. This program is designed to help low-to-moderate-income individuals and families achieve the dream of homeownership in eligible rural areas. Here are the key qualifications for obtaining a USDA loan in Kentucky:
Income Limits
To qualify for a USDA loan, applicants must not have an annual adjusted income greater than **115%** of the median household income for the area¹.
Employment
Applicants are expected to provide proof of stable income and employment for at least two years¹.
Credit Requirements
While there is no minimum credit score required, applicants must meet USDA’s guaranteed underwriting credit requirements. A fair consideration of the credit background is essential⁴.
Property Location
The property must be situated in an eligible rural area as defined by the USDA¹.
Property Standards
The home must be safe, sanitary, and structurally sound to qualify for a USDA loan¹.
Occupancy
Borrowers must agree to occupy the property as their primary residence³.
Legal Capacity
Applicants must have the legal capacity to incur a loan obligation³.
Citizenship
Applicants must meet citizenship or eligible noncitizen requirements³.
Debt-to-Income Ratio
Your monthly housing costs (mortgage principal and interest, property taxes, and insurance) must not exceed **29%** of your gross monthly income⁴.
Loan Limits
The USDA does not set specific maximum loan amounts for guaranteed mortgages. Instead, local limits are determined by a combination of the area USDA maximum income limit and the borrower’s debt-to-income ratios⁴.
The USDA loan program is a fantastic opportunity for those looking to buy a home in Kentucky’s rural areas. With no down payment required and flexible qualification criteria, it opens the door to homeownership for many who may not qualify for conventional loans.
For more detailed information or to apply for a USDA loan, it’s recommended to contact a local mortgage lender or visit the USDA Rural Development website.
This article provides a concise overview of the qualifications needed for a USDA loan in Kentucky. Prospective homebuyers should consult with a mortgage professional to understand the full application process and to determine their eligibility.
Notice of changes to eligible area maps for USDA Rural Development housing programs
USDA Rural Development has completed its 2020 decennial United States census review for all areas under its jurisdiction to identify areas that no longer qualify as rural for Kentucky USDA Rural Housing programs.
Based on the review of the areas within the state of Kentucky, using 2020 US census data, and rural area guidance located in Handbook HB-1-3550, Chapter 5, the rural eligibility designation has changed for the following areas:
Areas whose rural eligibility designations are changing from ineligible to eligible (these areas now qualify as rural for USDA Housing Programs):
The area/towns currently outside the city of Ashland, KY (Catlettsburg, West Fairview, Fairview, Westwood, Russell).
The areas/towns currently outside the city of Paducah, KY (Hendron and Farley).
The cities of Ashland, KY and Paducah, KY will remain ineligible.
Areas whose rural eligibility designation is changing from eligible to ineligible (these areas no longer qualify as rural for USDA Housing Programs):
Georgetown, KY – The city of Georgetown, KY, will no longer be eligible due to the population exceeding 35,000.
Changes become effective October 1, 2023.
The updated rural area map can now be viewed on our eligibility website. Users will need to click on the program, for example: “Single Family Housing Direct,” and then click on “Proposed Eligibility Areas” from the menu options.
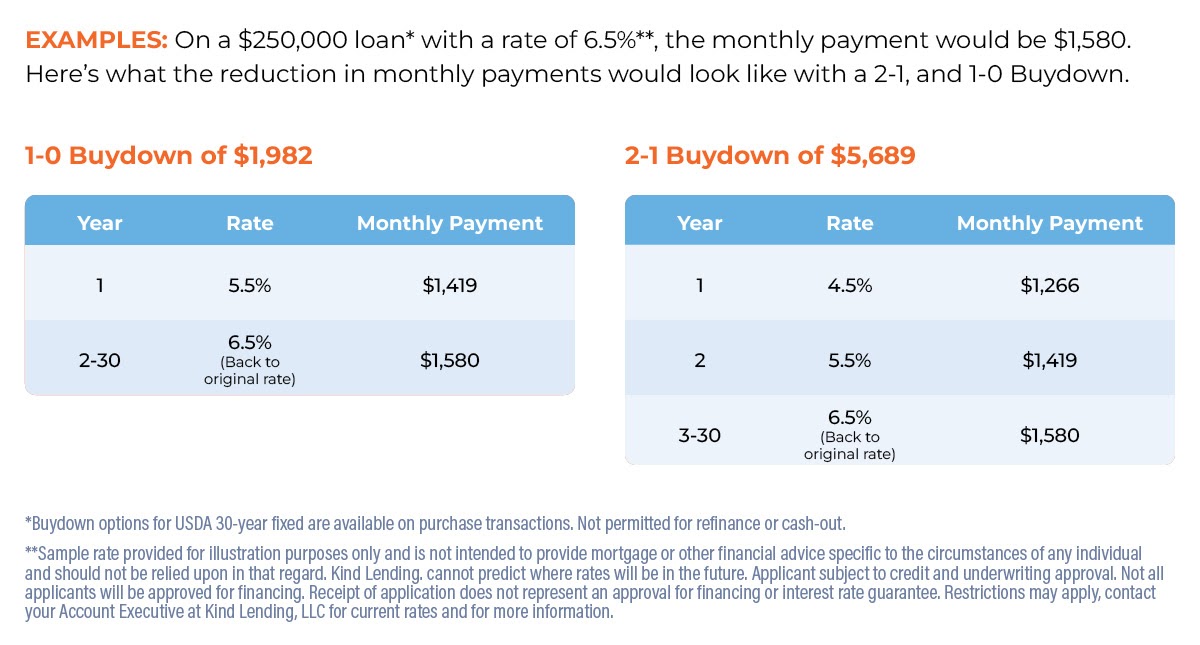
2-1 and 1-0 buydowns for Kentucky Rural Housing USDA RD loans Interest Rates.
What are Buydowns for Kentucky USDA RD Loans?
The Kentucky Rural Housing USDA Buydown Program provides simple financing options that lowers the interest rate on a mortgage for either 1 year (1-0) or 2 years (2-1), before it rises to the regular permanent rate. Specifics2-1, and 1-0 temporary interest rate buydowns are allowed on 30 year fixed-rate mortgages for principal residences, purchase only. Not permitted on refinance transactions.The seller or agent may provide funds for the temporary interest rate buydown, subject to standard interested party contribution limits.Lender paid buydowns are not offered.The borrower is qualified at the note rate fully amortized (not the buydown rate)Minimum credit score for loans with buydown is 620
Have Questions or Need Expert Advice? Text, email, or call me below:
Joel Lobb Mortgage Loan Officer
EVO Mortgage 10602 Timberwood Cir, Ste 3, Louisville, KY 40223
The view and opinions stated on this website belong solely to the authors, and are intended for informational purposes only. The posted information does not guarantee approval, nor does it comprise full underwriting guidelines. This does not represent being part of a government agency. The views expressed on this post are mine and do not necessarily reflect the view of my employer. Not all products or services mentioned on this site may fit all people. NMLS ID# 57916, (www.nmlsconsumeraccess.org).
Kentucky USDA loans are loans offered by the United States Department of Agriculture to those looking to buy homes in rural areas of Kentucky.
There are a few requirements and restrictions associated with this type of loan however, if you are afirst time home buyer in Kentucky with a limited income, no down payment and are looking to live in a rural part of Kentucky, this may be a good option for you to purchase a home going no money down and getting a 30 year fixed rate loan.
Income Requirements for USDA Loans in Kentucky
The Rural Housing USDA website provides an income eligibility calculatordepending on where you are looking for housing in the state of Kentucky. Because it is a nationally funded loan by the United States Government, the income restrictions will vary county-by-county but the loan recipient cannot make more than 115% of the median income for the area in which they are applying. There is also a chart you can consult that provides Kentucky USDA county income limits depending on the number of people in your home. Most Kentucky counties allow up to $122,800 for a household of one to four people, and up to $162,100 for a household of five to eight. The Northern Kentucky counties of Boone, Bracken, Campbell, Gallatin, Kenton and Pendleton allow more: $128,600 for one to four people and $169,800 for five to eight. These limits took effect July 13, 2026.
Households with 1-4 members have different limits as households with 5-8. Similarly, applicants living in high-cost counties will have a higher income limit than those living in counties with a more average cost of living.
Kentucky Score Requirements for a USDA Loan in Kentucky
USDA does not publish a minimum credit score anywhere in Handbook HB-1-3555. What actually drives your file is the underwriting recommendation USDA’s automated system, GUS, gives it. A 640 middle score will typically get a GUS Accept. Below 640 the file gets manually underwritten, which is still possible. Most lenders set a 640 floor as their own overlay, but that is the lender’s rule, not a USDA rule.
If the potential borrower has declared bankruptcy or foreclosure within the last 36 months, they would be ineligible for this type of loan.
If the mortgage was included in the Bankruptcy, sometimes the 36 month hold is ignored and you just have to make sure the property is out of your name before applying for a USDA loan
Can you get a USDA loan in Kentucky with a Previous Bankruptcy?
Chapter 7 bankruptcy, the bankruptcy must have been discharged at least 3 years prior to becoming eligible for a Kentucky USDA home loan.
Borrowers must be in a Chapter 13 bankruptcy for a minimum of 12 months, with documentation of 12 months of on time payments and a letter of authorization from the bankruptcy trustee authorizing you to enter into new debt.
In order to qualify for a USDA home loan after filing a Chapter 13 bankruptcy, additional documentation may be requested/required stating that the reason for the Chapter 13 filing was due to extenuating circumstances beyond the borrower’s control, temporary in nature and not likely to re-occur.
Home must be primary Residence.
Recipients must be U.S. Citizens, U.S. non-citizen nationals or Qualified Aliens to apply for this program. They must also agree to use the home as their primary residence and not as a rental property.
The property has to be residential. That covers single family homes, townhouses, condominiums, new construction, and manufactured homes. A condo project can be approved by FHA, VA, Fannie Mae or Freddie Mac, and it does not have to already be sitting on one of those lists. It can also qualify by being shown to meet one of those agencies’ standards. An attached townhome that is not part of a condominium regime does not need any project approval at all.
What areas of Kentucky Qualify for the USDA Loan Program?
The USDA provides a map of the where you can apply a USDA loans are eligible in Kentucky. The major metro areas of Jefferson County and Fayette County Kentucky are not eligible for Rural Housing Loans in Kentucky, along with some parts of Northern Kentucky next to Cincinnati; parts of Owensboro, Paducah, Bowling Green, Richmond, Frankfort, Winchester, Radcliff, Hopkinsville and Henderson Kentucky are not eligible.
If you have a property in mind, you can head over to the eligibility map to see if the home you are considering qualifies.
What are the advantages of USDA loans in Kentucky?
For many people in a low to middle-income bracket, saving for a down payment can be difficult. A USDA loan does not require the purchaser to put any money down toward the purchase price of a home. The government insures the loan in this case, should the borrower default, therefore the borrower is required to carry mortgage insurance during the life of the loan. The mortgage insurance for the USDA loan is provided at a more discounted rate than that required by traditional loans.
On USDA loans the mortgage insurance is 1% upfront, called a guarantee fee, and .35% monthly called an annual mortgage insurance fee to USDA. The beauty of USDA, is that it does not matter if you have a credit score of 640, or a credit score of 740, everyone pays the same premiums, unlike conventional loans.
They only offer 30 year fixed rates with no prepayment penalty, and usually the rates are very low and compare to FHA rates and much lower than conventional loans.
USDA loans take on average about 30 days to close, and the appraisal must meet FHA requirements. Home inspections are not required. Manufactured homes are allowed, and since May 5, 2025 that includes existing used units, not just brand new ones off a dealer lot. An existing manufactured home has to have been built within 20 years of your closing date, sit on a permanent foundation, never have been installed at another homesite, be at least 400 square feet, still carry both the HUD certification label and the HUD data plate, and have no alterations made after it left the factory other than an engineered porch or deck.
If you are an individual with disabilities who needs accommodation, or you are having difficulty using our website to apply for a loan, please contact us at 502-905-3708.
Disclaimer: No statement on this site is a commitment to make a loan. Loans are subject to borrower qualifications, including income, property evaluation, sufficient equity in the home to meet Loan-to-Value requirements, and final credit approval. Approvals are subject to underwriting guidelines, interest rates, and program guidelines and are subject to change without notice based on applicant’s eligibility and market conditions. Refinancing an existing loan may result in total finance charges being higher over the life of a loan. Reduction in payments may reflect a longer loan term. Terms of any loan may be subject to payment of points and fees by the applicant Equal Opportunity Lender. NMLS#57916 http://www.nmlsconsumeraccess.org/
— Some products and services may not be available in all states. Credit and collateral are subject to approval. Terms and conditions apply. This is not a commitment to lend. Programs, rates, terms and conditions are subject to change without notice. The content in this marketing advertisement has not been approved, reviewed, sponsored or endorsed by any department or government agency. Rates are subject to change and are subject to borrower(s) qualification.
Section 504 Repair Loan and Grant Program for Kentucky USDA RHS Loans
If you missed the live webinar to learn about recent changes to the Section 504 Single-Family Housing Repair Loan and Grant Program, the presentation slides from the webinar are available on the U.S. Department of Agriculture (USDA) Rural Development’s website. This information is for individuals and organizations, including nonprofits and public agencies, who work with affordable housing products such as weatherization, home repairs, and Section 504 application packaging.
The slides will provide information on the following:
An overview of recent changes to the Section 504 Single-Family Housing Repair Loan and Grant Program.
For a brief overview of the 504 program, please watch the USDA Helps You Make Home Repairs
Program Guidelines & Terms –Section 504 Loans
• Maximum outstanding 504 loan amount is $20,000
• Interest rate is fixed at 1%
• Maximum term of 20 years (term and payment is based upon the
family budget)
• Appraisal and escrow account is required for loans over $15,000
• Flood insurance is required for properties located in a flood zone
• Mortgage, title work and closing agent required for loans of
$7,500 or more
• Mortgage is filed for loans of $7,500 and over
• Assets above $15,000 ($20,000 for elderly/disabled households)
must be applied toward repairs.
• Residential Mortgage Credit Reports are ordered by Agency for
loans of $7,500 and over (RMCR fee paid by Rural Development
General Eligibility Criteria – Section 504 Loans
• Household income must not exceed “very low” income
limits; < 50% HUD median income
• Applicant must own home (to include site when
considering manufactured housing) and occupy house on a
permanent basis
• Demonstrate repayment ability based upon a family budget
• Stable and dependable source of income
• Acceptable credit – reasonable ability and willingness to
meet debt obligations
• Meet asset limitations (15K non-elderly and $20K elderly*)
Program Guidelines & Terms –Section 504 Grant
• Maximum cumulative lifetime grant assistance is $7,500
• Grantee must sign Grant Agreement requiring occupancy
of home for 3 years
• No lien on property
• Repairs to remove health and safety hazards or to make the
home accessible and useable for household members with
disabilities.
General Eligibility Criteria – Section 504 Grants
• At least one applicant must be 62 years of age or older.
• Household income must not exceed “very low” income limits;
< 50% HUD median income
• Applicant must own home (to include site when considering
manufactured housing) and occupy house on a permanent basis
• Repairs must be necessary to remove health and safety hazards or
to make the home accessible and useable for household members
with disabilities.
• Must demonstrate a lack of repayment ability based upon a
household budget.
• Meet asset limitations (15K non-elderly and $20K elderly*)
• No outstanding federal judgments
SECTION 504 PROPERTY REQUIREMENTS
• Must be modest for the area; market value cannot be in
excess of USDA established area loan limit
• Property must be located in a designated rural area
• Must not have an in-ground swimming pool
• If the property has income producing land or structures, we
may use loan/grant funds as long as repairs are used for the
residential portion of the home.
• Mobile or manufactured homes must be on a permanent
foundation or be placed on a permanent foundation with
loan or grant funds.
For additional program Information, please visit the following USDA webpages: