Kentucky Mortgage Underwriting: Key Guidelines Explained

Understanding Kentucky Mortgage underwriting guidelines

All lending institutions have different Underwriting Guidelines set in place when reviewing a borrower’s financial history to determine the likelihood of receiving on-time payments. The primary items reviewed are the following 5 areas below:

1. Income

2. Debt

3. Credit History

4. Savings

5. Debt vs Income Ratio


Income

Income is one of the most important variables a lender will examine because it is used to repay the loan. Income is reviewed for the type of work, length of employment, educational training required, and opportunity for advancement. An underwriter will look at the source of income and the likelihood of its continuance to arrive at a gross monthly figure.

Salary and Hourly Wages – Calculated on a gross monthly basis, prior to income tax deductions.

Part-time and Second Job Income – Not usually considered unless it is in place for 12 to 24 straight months. Lenders view part-time income as a strong compensating factor.

Commission, Bonus and Overtime Income – Can only be used if received for two previous years. Further, an employer must verify that it is likely to continue. A 24-month average figure is used.

Retirement and Social Security Income – Must continue for at least three years into the future to be considered. If it is tax free, it can be grossed up to an equivalent gross monthly figure. Multiply the net amount by 1.20%.

Alimony and Child Support Income – Must be received for the 12 previous months and continue for the next 36 months. Lenders will require a divorce decree and a court printout to verify on-time payments.

Notes Receivable, Interest, Dividend and Trust Income – Proof of receiving funds for 12 previous months is required. Documentation showing income due for 3 more years is also necessary. Rental Income – Cannot come from a Primary Residence roommate. The only acceptable source is from an investment property. A lender will use 75% of the monthly rent and subtract ownership expenses. The Schedule E of a tax return is used to verify the figures. If a home rented recently, a copy of a current month-to-month lease is acceptable.

Automobile Allowance and Expense Account Reimbursements – Verified with 2 years tax returns and reduced by actual expenses listed on the income tax return Schedule C.

Education Expense Reimbursements – Not considered income. Only viewed as slight compensating factor.

Self-Employment Income – Lenders are very careful in reviewing self-employed borrowers. Two years minimum ownership is necessary because two years is considered a representative sample. Lenders use a 2-year average monthly income figure from the Adjusted Gross Income on the tax returns. A lender may also add back additional income for depreciation and one-time capital expenses. Self-employed borrowers often have difficulty qualifying for a mortgage due to large expense write offs. A good solution to this challenge used to be the No Income Verification Loan, but there are very few of these available any more given the tightened lending standards in the current economy. NIV loan programs can be studied in the Mortgage Program section of the library.

2. Debt

An applicant’s liabilities are reviewed for cash flow. Lenders need to make sure there is enough income for the proposed mortgage payment, after other revolving and installment debts are paid.

All loans, leases, and credit cards are factored into the debt calculation. Utilities, insurance, food, clothing, schooling, etc. are not.

If a loan has less than 10 months remaining, a lender will usually disregard it.

The minimum monthly payment listed on a credit card bill is the figure used, not the payment made.

An applicant who co-borrowed for a friend or relative is accountable for the payment. If the applicant can show 12 months of on-time cancelled checks from the co-borrower, the debt will not count.

Loans can be paid off to qualify for a mortgage, but credit cards sometimes cannot (varies by lender). The reasoning is that if the credit card is paid off, the credit line still exists, and the borrower can run up debt after the loan is closed.

A borrower with fewer liabilities is thought to demonstrate superior cash management skills.

Credit History


Most lenders require a residential merged credit report (RMCR) from the 3 main credit bureaus: Trans Union, Equifax, and Experian. They will order one report which is a blending of all three credit bureaus and is easier to read than the individual reports. This “blended” credit report also searches public records for liens, judgments, bankruptcies and foreclosures. See our credit report index.Credit report in hand, an underwriter studies the applicant’s credit to determine the likelihood of receiving an on-time mortgage payment. Many studies have shown that past performance is a reflection of future expectations. Hence, most lenders now use a national credit scoring system, typically the FICO score, to evaluate credit risk. If you’re worried about credit scoring, see our articles on it.

The mortgage lending process, once very forgiving, has tightened lending standards considerably. A person with excellent credit, good stability, and sufficient documentable income to make the payments comfortably will usually qualify for an “A” paper loan. “A Paper”, or conforming loans, make up the majority of loans in the U.S. and are loans that must conform to the guidelines set by Fannie Mae or Freddie Mac in order to be saleable by the lender. Such loans must meet established and strict requirements regarding maximum loan amount, down payment amount, borrower income and credit requirements and suitable properties. Loans that do not meet the credit and/or income requirements of conforming “A-paper” loans are known as non-conforming loans and are often referred to as “B”, “C” and “D” paper loans depending on the borrower’s credit history and financial capacity.

Here are some rules of thumb most lenders follow:

12 plus months positive credit will usually equal an A paper loan program, depending on the overall credit. FHA loans usually follow this guideline more often than conventional loans.

Unpaid collections, judgments and charge offs must be paid prior to closing an A paper loan. The only exception is if the debt was due to the death of a primary wage earner, or the bill was a medical expense.

If a borrower has negotiated an acceptable payment plan and has made on time payments for 6 to 12 months, a lender may not require a debt to be paid off prior to closing.

Credit items usually are reported for 7 years. Bankruptcies expire after 10 years.

Foreclosure – 5 years from the completion date. From the fifth to seventh year following the foreclosure completion date, the purchase of a principal residence is permitted with a minimum 10% down and 680 FICO score. The purchase of a second or investment property is not permitted for 7 years. Limited cash out refinances are permitted for all occupancy types.

Pre-foreclosure (Short Sale) – 2 years from the completion date (no exceptions or extenuating circumstances).

Deed-in-Lieu of Foreclosure – 4-year period from the date the deed-in-lieu is executed. From the fifth to the seventh year following the execution date the borrower may purchase a property secured by a principal residence, second home or investment property with the greater of 10 percent minimum down payment or the minimum down payment required for the transaction. Limited cash out and cash out refinance transactions secured by a principal residence, second home or investment property are permitted pursuant to the eligibility requirements in effect at that time.

Chapter 7 Bankruptcy – A borrower is eligible for an A paper loan program 4 years after discharge or dismissal, provided they have reestablished credit and have maintained perfect credit after the bankruptcy.

Chapter 13 Bankruptcy – 2 years from the discharge date or 4 years from the dismissal date.

Multiple Bankruptcies- 5 years from the most recent dismissal or discharge date for borrowers with more than one filing in the past 7 years.

The good credit of a co-borrower does not offset the bad credit of a borrower.

Credit scores usually range from 400 to 800. Changes to lending standards are occurring on a daily basis as a result of tightening lending standards and can vary from lender-to-lender– so this information should be considered simply a guideline. For conforming loans, most lenders will lend down to a FICO of 620, with additional rate hits for the lower-end credit scores and loan-to-values. When you are borrowing more than 80%, they typically will not lend if you have a FICO below 680. The FHA/VA program just changed their minimum required FICO to 620, unless you are qualifying a borrower with non-traditional credit. The few non-conforming loan programs that are still available typically require 30% down payment with a minimum FICO of 700 for self-employed and 650 for W-2 employees, and the loan-to-value will change with the loan amount.

Lenders evaluate savings for three reasons.

The more money a borrower has after closing, the greater the probability of on-time payments.

Most loan programs require a minimum borrower contribution.

Lenders want to know that people have invested their own into the house, making it less likely that they will walk away from their life’s savings. They analyze savings documents to insure the applicant did not borrow the funds or receive a gift.

Lenders look at the following types of accounts and assets for down payment funds:

Checking and Savings – 90 days seasoning in a bank account is required for these funds. Gifts and Grants – After a borrower’s minimum contribution, a gifts or grant is permitted.

Sale of Assets – Personal property can be sold for the required contribution. The property should be appraised, and a bill of sale is required. Also, a copy of the received check and a deposit slip are needed.

Secured Loans – A loan secured by property is also an acceptable source of closing funds.

IRA, 401K, Keogh & SEP – Any amount that can be accessed is an acceptable source of funds.
Sweat Equity and Cash On Hand – Generally not acceptable. FHA programs allow it in special circumstances.
Sale Of Previous Home – Must close prior to new home for the funds to be used. A lender will ask for a listing contract, sales contract, or HUD 1 closing statement.

The percentage of one’s debt to income is one of the most important factors when underwriting a loan. Lenders have determined that a house payment should not exceed approximately 30% of Gross Monthly Income. Gross Monthly Income is income before taxes are taken out. Furthermore, a house payment plus minimum monthly revolving and installment debt should be less than 40% of Gross Monthly Income (this figure varies from 35%-41% contingent on the source of financing).

Example

An applicant has $4,500 gross monthly income. The maximum mortgage payment is:

$4500 X .30 = $1350

Their total debts come to:

$500 Car

$20 Visa

$30 Sears

$75 Master Card

—————-

$625 per month.

Remember, their total debts (mortgage plus other debts) must be less than or equal to 40% of their gross monthly income.

$2,800 X .40 = $1800

$1800 is the maximum debt the borrower can have, debts and mortgage payments combined. Can the borrower keep all their debts and have the maximum mortgage payment allowed? NO!

In this case, the borrower, since they have high debts, must adjust the maximum mortgage payment downward, because:

$625 debts

$1350 mortgage
————-

$1975 – which is more than the $1800 (40% of gross debt) we calculated above.

The maximum mortgage payment is therefore:

$1800 – $625 (monthly debt) = $1175.

Some restrictions apply. Ask for details. Loan decision is subject to satisfactory appraisal and title review and no change in financial condition. This is not an offer for extension of credit or a commitment to lend. Equal Housing Opportunity.
This communication is provided to you for informational purposes only and should not be relied upon by you.
Joel Lobb
Mortgage Broker – FHA, VA, USDA, KHC, Fannie Mae
EVO Mortgage • Helping Kentucky Homebuyers Since 2001
📞 Call/Text: 502-905-3708
📧 Email: kentuckyloan@gmail.com
🌐 Website: www.mylouisvillekentuckymortgage.com
🏠 Address: 10602 Timberwood Cir, Ste 3, Louisville, KY 40223
NMLS #57916 | Company NMLS #1738461
Free Info & Homebuyer Advice →
Kentucky Mortgage Loan Expert
FHA | VA | USDA | KHC Down Payment Assistance | Fannie Mae
Equal Housing Lender. This is not a commitment to lend. All loans are subject to credit approval and program requirements.
Disclaimer: No statement on this site is a commitment to make a loan. Loans are subject to borrower qualifications, including income, property evaluation, sufficient equity in the home to meet Loan-to-Value requirements, and final credit approval. Approvals are subject to underwriting guidelines, interest rates, and program guidelines and are subject to change without notice based on applicant’s eligibility and market conditions. Refinancing an existing loan may result in total finance charges being higher over the life of a loan. Reduction in payments may reflect a longer loan term. Terms of any loan may be subject to payment of points and fees by the applicant  Equal Opportunity Lender. NMLS#57916http://www.nmlsconsumeraccess.org/

How to Get Approved for a USDA Mortgage Loan in Kentucky

Kentucky USDA Mortgage Loan Guide

Your Complete Roadmap to Zero-Down Financing in 2026

What Is a USDA Mortgage Loan?

The USDA Rural Development Guaranteed Loan Program is designed to help Kentucky families purchase homes in eligible rural areas. With over 20 years of experience assisting more than 1,300 Kentucky families, I’ve successfully guided hundreds through USDA loans across all 120 counties.

✓ 100% financing (zero down payment)
✓ Below-market fixed interest rates
✓ Flexible credit requirements
✓ Low mortgage insurance (0.35%)
✓ Financing of closing costs possible
✓ Seller concessions allowed

If you’re a first-time homebuyer looking for a true no-money-down option without VA benefits, USDA is your strongest choice.

Property Eligibility

The property must be located in a USDA-eligible rural zone. The excellent news for Kentucky buyers: most of the state qualifies. While Louisville and Lexington city centers are ineligible, surrounding suburban areas typically qualify.

Typically Eligible Areas

  • Most of Hardin, Meade, Breckenridge, Grayson, Nelson, Spencer, and Shelby Counties
  • Large portions of Bullitt County outside immediate Louisville limits
  • Nearly all of Eastern and Western Kentucky
  • Suburban pockets around Lexington, Georgetown, Winchester, and Nicholasville
Check Eligibility: Use the USDA property eligibility map to verify any address before making an offer. This step saves time and ensures you’re pursuing viable properties.

Income Limits for 2026

Your total household income must not exceed the USDA county limit for your family size. USDA counts all household income, including spouses, adult children, part-time earnings, and bonuses.

Household Size 2026 Income Limit Range
1–4 People Up to approximately $119,850 for 1-4 members and $158,250 for 5-8 members
5–8 People Up to approximately $ $119,850 for 1-4 members and $158,250 for 5-8 members

Note: Limits vary by county. Contact me for your specific county’s limits.

Credit Score Requirements

While USDA doesn’t publish a minimum credit score, Kentucky lenders follow these general guidelines:

640+ Credit Score — Easiest Path to Approval

  • Eligible for automated approval through GUS (USDA’s system)
  • More flexible debt-to-income ratios
  • Faster underwriting timeline

580–639 — Possible With Manual Underwriting

Approvals in this range require strong supporting documentation:

  • Perfect rental history
  • No late payments in the past 12 months
  • Low overall debt
  • Stable employment history

Below 580 — Case-by-Case Review

Not impossible, but uncommon. Success requires significant compensating factors and strong manual underwriting review.

Employment Rules

Underwriters typically require a 2-year work history, though it doesn’t need to be at the same job. USDA is flexible about career transitions within reason.

USDA Accepts

  • Job changes within the same field or industry
  • Recent graduates working in their trained field
  • 12+ months of consistent income
  • Self-employed borrowers (with 2 years of tax returns)

Red Flags to Avoid

  • Job gaps longer than 60 days
  • Declining income trends over time
  • Multiple unrelated job switches

Debt-to-Income Ratio Requirements

Your DTI is calculated as a percentage of your gross monthly income.

DTI Type Standard Limit With Strong Credit (GUS Approve)
Front-End (Housing Only) 29% Up to 29–34%
Back-End (All Debt) 41% 44%+

Manual underwriting files must stay closer to standard limits, while automated approvals offer more flexibility.

Bankruptcy & Foreclosure Waiting Periods

If you’ve experienced financial hardship, USDA has established waiting periods before approval:

Credit Event Waiting Period
Chapter 7 Bankruptcy 3 Years from Discharge
Chapter 13 Bankruptcy 12 Months of On-Time Payments + Trustee Approval
Foreclosure 3 Years from Sale Date
Short Sale 3 Years (Typical)
Medical collections and older accounts rarely require payoff. Your individual circumstances matter—let’s review your specific situation.

Property Condition & Appraisal Requirements

Your home must be safe, sound, and sanitary. The USDA appraiser evaluates:

  • Roof condition and remaining lifespan
  • Foundation stability and integrity
  • Electrical system safety
  • Plumbing functionality
  • Adequate heating system for the entire home
  • Absence of active termite damage
  • No peeling lead-based paint

Most repairs can be handled by the seller before closing. This is a negotiation point in your offer.

The USDA Loan Process

1Pre-Qualification

Credit check, income estimate, DTI calculation, and review of eligible areas

2Full Pre-Approval

Gather pay stubs, W-2s, tax returns, bank statements, and photo ID

3Find Your Home

Use eligibility maps to confirm the property qualifies before making an offer

4Loan Application & Underwriting

Rate lock, appraisal order, document review, and GUS findings

5USDA Final Approval

Conditional Commitment issued (typically 2–7 days)

6Closing Day

Sign final paperwork, receive keys, and move into your new home

Timeline: Most Kentucky USDA loans close within 30–45 days from application.

Frequently Asked Questions

Do I need a down payment?

No—USDA loans provide 100% financing with zero down payment required.

Can I buy in Louisville or Lexington?

City centers are ineligible, but many surrounding suburbs qualify. Always verify the property address on the USDA eligibility map before making an offer.

What credit score do I need?

640+ is ideal for streamlined approval. Manual underwriting may consider scores down to 580 with strong compensating factors.

Can the seller help with closing costs?

Yes—USDA allows seller concessions, and some closing costs can be financed if the appraisal supports it.

How long does the process take?

Most Kentucky USDA loans close in 30–45 days from application.

Are there down payment assistance programs?

Yes. Kentucky Housing Corporation (KHC) programs offer additional assistance for qualified first-time homebuyers to further reduce upfront costs.

Ready to Get Pre-Approved?

Let’s explore your USDA lending options with personalized guidance and same-day approvals.

Call or Text: 502-905-3708
Email: kentuckyloan@gmail.com

Serving qualified homebuyers across all 120 Kentucky counties

Joel Lobb, Mortgage Loan Officer | Specialist in Kentucky FHA, VA, USDA, KHC & Fannie Mae Loans

EVO Mortgage — Helping Kentucky Homebuyers Since 2001

NMLS Personal ID: 57916 | Company NMLS ID: 1738461 | Equal Housing Lender

This website is not endorsed by the USDA, FHA, VA, or any government agency. It is an independent educational resource.

This is not a commitment to lend. All loans subject to credit approval and USDA program guidelines.

 Buying Your First House in Kentucky: Loan Programs and Requirements

Buying Your First House in Kentucky with the recommend mortgage loan programs below

A Guide to Buying Your First House in Kentucky: Loan Programs and Requirements
Buying your first home in Kentucky is an exciting milestone, but it can also feel overwhelming. Fortunately, there are several loan programs and resources available to make the process smoother. This guide will walk you through the most popular loan programs and their requirements, helping you take confident steps toward homeownership.

  1. FHA Loan: A Flexible Option for First-Time Buyers
    The Federal Housing Administration (FHA) loan is popular among first-time homebuyers due to its lenient requirements.
    Key Requirements:
    Credit Score: Minimum of 580 with 3.5% down payment. Scores between 500-579 require a 10% down payment.
    Down Payment: 3.5% minimum.
    Mortgage Insurance: Requires both an upfront premium and monthly mortgage insurance.
    Debt-to-Income (DTI) Ratio: Typically up to 43%.
    Benefits:
    Lower credit score requirements.
    Smaller down payment.
    Flexible income guidelines.
  2. VA Loan: No Money Down for Eligible Veterans
    The VA Loan is a fantastic option for Kentucky veterans, active-duty service members, and their spouses. It’s backed by the Department of Veterans Affairs.
    Key Requirements:
    Credit Score: No official minimum, but lenders often look for 580-620.
    Down Payment: $0 (no down payment required).
    Certificate of Eligibility (COE): Required to prove eligibility.
    Mortgage Insurance: None, but a VA funding fee applies.
    Benefits:
    No down payment.
    No private mortgage insurance (PMI).
    Competitive interest rates.
  3. USDA Loan: Ideal for Rural Homebuyers
    The USDA Rural Development Loan is perfect for buyers looking to live in rural or suburban areas in Kentucky.
    Key Requirements:
    Credit Score: Generally 620 or higher.
    Income Limits: Household income must not exceed the area’s median income.
    Location: The property must be in a USDA-eligible rural area.
    Debt-to-Income Ratio: Up to 41%.
    Benefits:
    $0 down payment.
    Affordable mortgage insurance.
    Competitive fixed interest rates.
  4. Kentucky Housing Corporation (KHC) Programs
    The Kentucky Housing Corporation offers down payment assistance and loan options to first-time buyers.
    KHC Loan Options:
    KHC FHA or Conventional Loans: Competitive rates and assistance programs.
    Down Payment Assistance: Up to $10,000 in assistance for qualifying borrowers.
    Key Requirements:
    Credit Score: Minimum 620 for most programs.
    Income Limits: Vary by program and household size.
    Property Type: Must be a primary residence.
  5. Conventional Loan: A Strong Option for Higher Credit Scores
    Conventional loans, offered through private lenders, are great for buyers with stronger credit profiles.
    Key Requirements:
    Credit Score: Minimum 660.
    Down Payment: As low as 3% with first-time buyer programs.
    Mortgage Insurance: Required if down payment is less than 20%.
    Benefits:
    Lower interest rates for strong credit scores.
    Option to cancel PMI once equity reaches 20%.
    Check Your Credit Score: Understand where you stand. If needed, work on improving your score before applying.
    Determine Your Budget: Get pre-approved for a mortgage to understand your price range.
    Explore Loan Options: Compare FHA, VA, USDA, KHC, and Conventional loans.
    Find Down Payment Assistance: Ask about programs like KHC’s assistance or grants.
    Work with a Trusted Mortgage Broker: Consider partnering with someone like Joel Lobb, a Kentucky-based mortgage expert specializing in first-time buyer programs.
    Conclusion
    Buying your first home in Kentucky doesn’t have to be intimidating. With programs like FHA, VA, USDA, and KHC, you can find a loan that fits your financial situation and homeownership goals.
    Take the first step today by getting pre-approved, exploring your options, and partnering with a knowledgeable mortgage expert.
    For more details or assistance, feel free to reach out to a trusted loan officer like Joel Lobb to guide you every step of the way.


1 –  Email – kentuckyloan@gmail.com 
2.   Call/Text – 502-905-3708

Joel Lobb
Mortgage Loan Officer – Expert on Kentucky Mortgage Loans


🌐 Website: www.mylouisvillekentuckymortgage.com
🏢 Address: 10602 Timberwood Cir, Ste 3, Louisville, KY 40223

Evo Mortgage
Company NMLS# 1738461
Personal NMLS# 57916

For assistance with Kentucky mortgage loans, reach out via email, call, or text Joel Lobb directly.

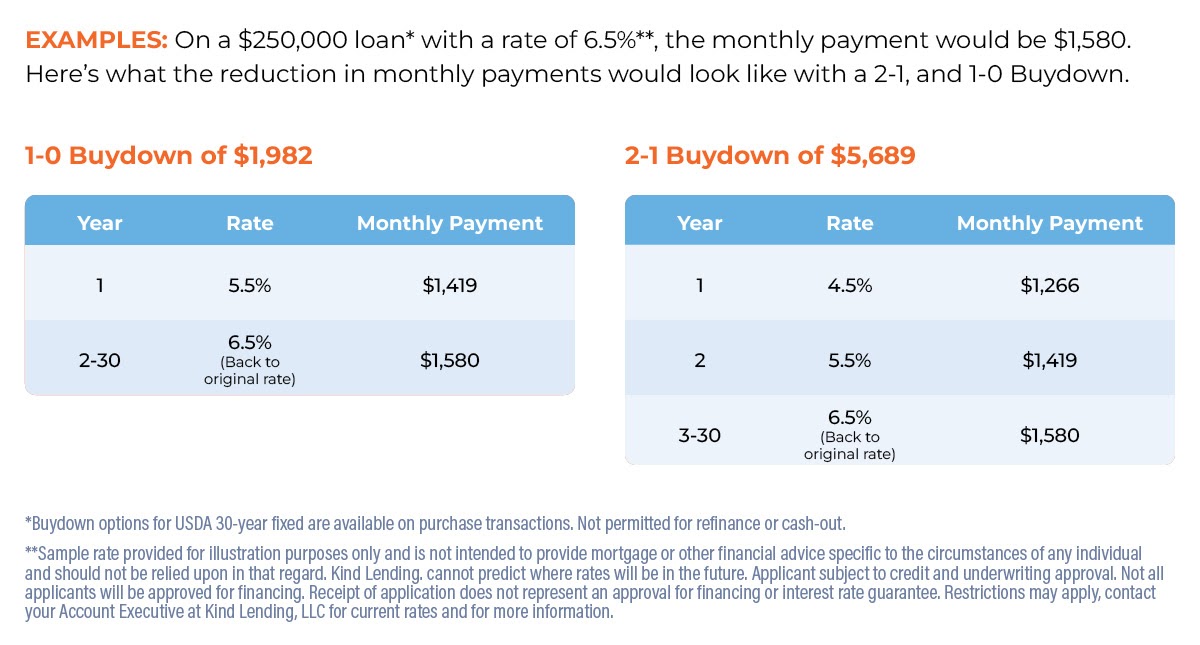
Kentucky Rural Housing USDA Buydown Program

2-1 and 1-0 buydowns for Kentucky Rural Housing USDA RD loans Interest Rates.
What are Buydowns for Kentucky USDA RD Loans?

The Kentucky Rural Housing USDA Buydown Program provides simple financing options that lowers the interest rate on a mortgage for either 1 year (1-0) or 2 years (2-1), before it rises to the regular permanent rate. Specifics2-1, and 1-0 temporary interest rate buydowns are allowed on 30 year fixed-rate mortgages for principal residences, purchase only. Not permitted on refinance transactions.The seller or agent may provide funds for the temporary interest rate buydown, subject to standard interested party contribution limits.Lender paid buydowns are not offered.The borrower is qualified at the note rate fully amortized (not the buydown rate)Minimum credit score for loans with buydown is 620
2-1 and 1-0 buydowns for USDA RD loans.      What are Buydowns for USDA RD Loans?  The USDA Buydown Program at Kind Lending provides simple financing options that lowers the interest rate on a mortgage for either 1 year (1-0) or 2 years (2-1), before it rises to the regular permanent rate.    Specifics  2-1, and 1-0 temporary interest rate buydowns are allowed on 30 year fixed-rate mortgages for principal residences, purchase only. Not permitted on refinance transactions. The seller or agent may provide funds for the temporary interest rate buydown, subject to standard interested party contribution limits. Lender paid buydowns are not offered. The borrower is qualified at the note rate fully amortized (not the buydown rate) Minimum credit score for loans with buydown is 640

Have Questions or Need Expert Advice? Text, email, or call me below:

Joel Lobb
Mortgage Loan Officer

EVO Mortgage
10602 Timberwood Cir, Ste 3, Louisville, KY 40223
Text or call: 502-905-3708
email: kentuckyloan@gmail.com
NMLS #57916 | Company NMLS #1738461
www.nmlsconsumeraccess.org
Equal Housing Lender

http://www.mylouisvillekentuckymortgage.com/

The view and opinions stated on this website belong solely to the authors, and are intended for informational purposes only. The posted information does not guarantee approval, nor does it comprise full underwriting guidelines. This does not represent being part of a government agency. The views expressed on this post are mine and do not necessarily reflect the view of my employer. Not all products or services mentioned on this site may fit all people.
NMLS ID# 57916, (www.nmlsconsumeraccess.org).

Who is eligible for a Rural Housing Loan in Kentucky?

Rural Housing Loan in Kentucky

Kentucky USDA loans are loans offered by the United States Department of Agriculture to those looking to buy homes in rural areas of Kentucky.

There are a few requirements and restrictions associated with this type of loan however, if you are a first time home buyer in Kentucky with a limited income, no down payment and are looking to live in a rural part of Kentucky, this may be a good option for you to purchase a home going no money down and getting a 30 year fixed rate loan.

Income Requirements for USDA Loans in Kentucky

The Rural Housing USDA website provides an income eligibility calculator depending on where you are looking for housing in the state of Kentucky. Because it is a nationally funded loan by the United States Government, the income restrictions will vary county-by-county but the loan recipient cannot make more than 115% of the median income for the area in which they are applying. There is also a chart you can consult that provides Kentucky USDA county income limits depending on the number of people in your home. Most Kentucky counties allow up to $122,800 for a household of one to four people, and up to $162,100 for a household of five to eight. The Northern Kentucky counties of Boone, Bracken, Campbell, Gallatin, Kenton and Pendleton allow more: $128,600 for one to four people and $169,800 for five to eight. These limits took effect July 13, 2026.

Households with 1-4 members have different limits as households with 5-8. Similarly, applicants living in high-cost counties will have a higher income limit than those living in counties with a more average cost of living.

Kentucky Score Requirements for a USDA Loan in Kentucky

USDA does not publish a minimum credit score anywhere in Handbook HB-1-3555. What actually drives your file is the underwriting recommendation USDA’s automated system, GUS, gives it. A 640 middle score will typically get a GUS Accept. Below 640 the file gets manually underwritten, which is still possible. Most lenders set a 640 floor as their own overlay, but that is the lender’s rule, not a USDA rule.

If the potential borrower has declared bankruptcy or foreclosure within the last 36 months, they would be ineligible for this type of loan.

If the mortgage was included in the Bankruptcy, sometimes the 36 month hold is ignored and you just have to make sure the property is out of your name before applying for a USDA loan

Can you get a USDA loan in Kentucky with a Previous Bankruptcy?

Chapter 7 bankruptcy, the bankruptcy must have been discharged at least 3 years prior to becoming eligible for a Kentucky USDA home loan.

Borrowers must be in a Chapter 13 bankruptcy for a minimum of 12 months, with documentation of 12 months of on time payments and a letter of authorization from the bankruptcy trustee authorizing you to enter into new debt.

In order to qualify for a USDA home loan after filing a Chapter 13 bankruptcy, additional documentation may be requested/required stating that the reason for the Chapter 13 filing was due to extenuating circumstances beyond the borrower’s control, temporary in nature and not likely to re-occur.

Home must be primary Residence.

Recipients must be U.S. Citizens, U.S. non-citizen nationals or Qualified Aliens to apply for this program. They must also agree to use the home as their primary residence and not as a rental property.

The property has to be residential. That covers single family homes, townhouses, condominiums, new construction, and manufactured homes. A condo project can be approved by FHA, VA, Fannie Mae or Freddie Mac, and it does not have to already be sitting on one of those lists. It can also qualify by being shown to meet one of those agencies’ standards. An attached townhome that is not part of a condominium regime does not need any project approval at all.

What areas of Kentucky Qualify for the USDA Loan Program?

The USDA provides a map of the where you can apply a USDA loans are eligible in Kentucky. The major metro areas of Jefferson County and Fayette County Kentucky are not eligible for Rural Housing Loans in Kentucky, along with some parts of Northern Kentucky next to Cincinnati; parts of Owensboro, Paducah, Bowling Green, Richmond, Frankfort, Winchester, Radcliff, Hopkinsville and Henderson Kentucky are not eligible.

If you have a property in mind, you can head over to the eligibility map to see if the home you are considering qualifies.

What are the advantages of USDA loans in Kentucky?

For many people in a low to middle-income bracket, saving for a down payment can be difficult. A USDA loan does not require the purchaser to put any money down toward the purchase price of a home. The government insures the loan in this case, should the borrower default, therefore the borrower is required to carry mortgage insurance during the life of the loan. The mortgage insurance for the USDA loan is provided at a more discounted rate than that required by traditional loans.

On USDA loans the mortgage insurance is 1% upfront, called a guarantee fee, and .35% monthly called an annual mortgage insurance fee to USDA. The beauty of USDA, is that it does not matter if you have a credit score of 640, or a credit score of 740, everyone pays the same premiums, unlike conventional loans.

They only offer 30 year fixed rates with no prepayment penalty, and usually the rates are very low and compare to FHA rates and much lower than conventional loans.

USDA loans take on average about 30 days to close, and the appraisal must meet FHA requirements. Home inspections are not required. Manufactured homes are allowed, and since May 5, 2025 that includes existing used units, not just brand new ones off a dealer lot. An existing manufactured home has to have been built within 20 years of your closing date, sit on a permanent foundation, never have been installed at another homesite, be at least 400 square feet, still carry both the HUD certification label and the HUD data plate, and have no alterations made after it left the factory other than an engineered porch or deck.

screenshot_20201203-145606

Joel Lobb


Mortgage Loan Officer

EVO Mortgage

10602 Timberwood Cir, Ste 3

Louisville, KY 40223

NMLS #57916 | Company NMLS #1738461

Equal Housing Lender


Text/call 502-905-3708

kentuckyloan@gmail.com

If you are an individual with disabilities who needs accommodation, or you are having difficulty using our website to apply for a loan, please contact us at 502-905-3708.

Disclaimer: No statement on this site is a commitment to make a loan. Loans are subject to borrower qualifications, including income, property evaluation, sufficient equity in the home to meet Loan-to-Value requirements, and final credit approval. Approvals are subject to underwriting guidelines, interest rates, and program guidelines and are subject to change without notice based on applicant’s eligibility and market conditions. Refinancing an existing loan may result in total finance charges being higher over the life of a loan. Reduction in payments may reflect a longer loan term. Terms of any loan may be subject to payment of points and fees by the applicant Equal Opportunity Lender. NMLS#57916 http://www.nmlsconsumeraccess.org/

— Some products and services may not be available in all states. Credit and collateral are subject to approval. Terms and conditions apply. This is not a commitment to lend. Programs, rates, terms and conditions are subject to change without notice. The content in this marketing advertisement has not been approved, reviewed, sponsored or endorsed by any department or government agency. Rates are subject to change and are subject to borrower(s) qualification.